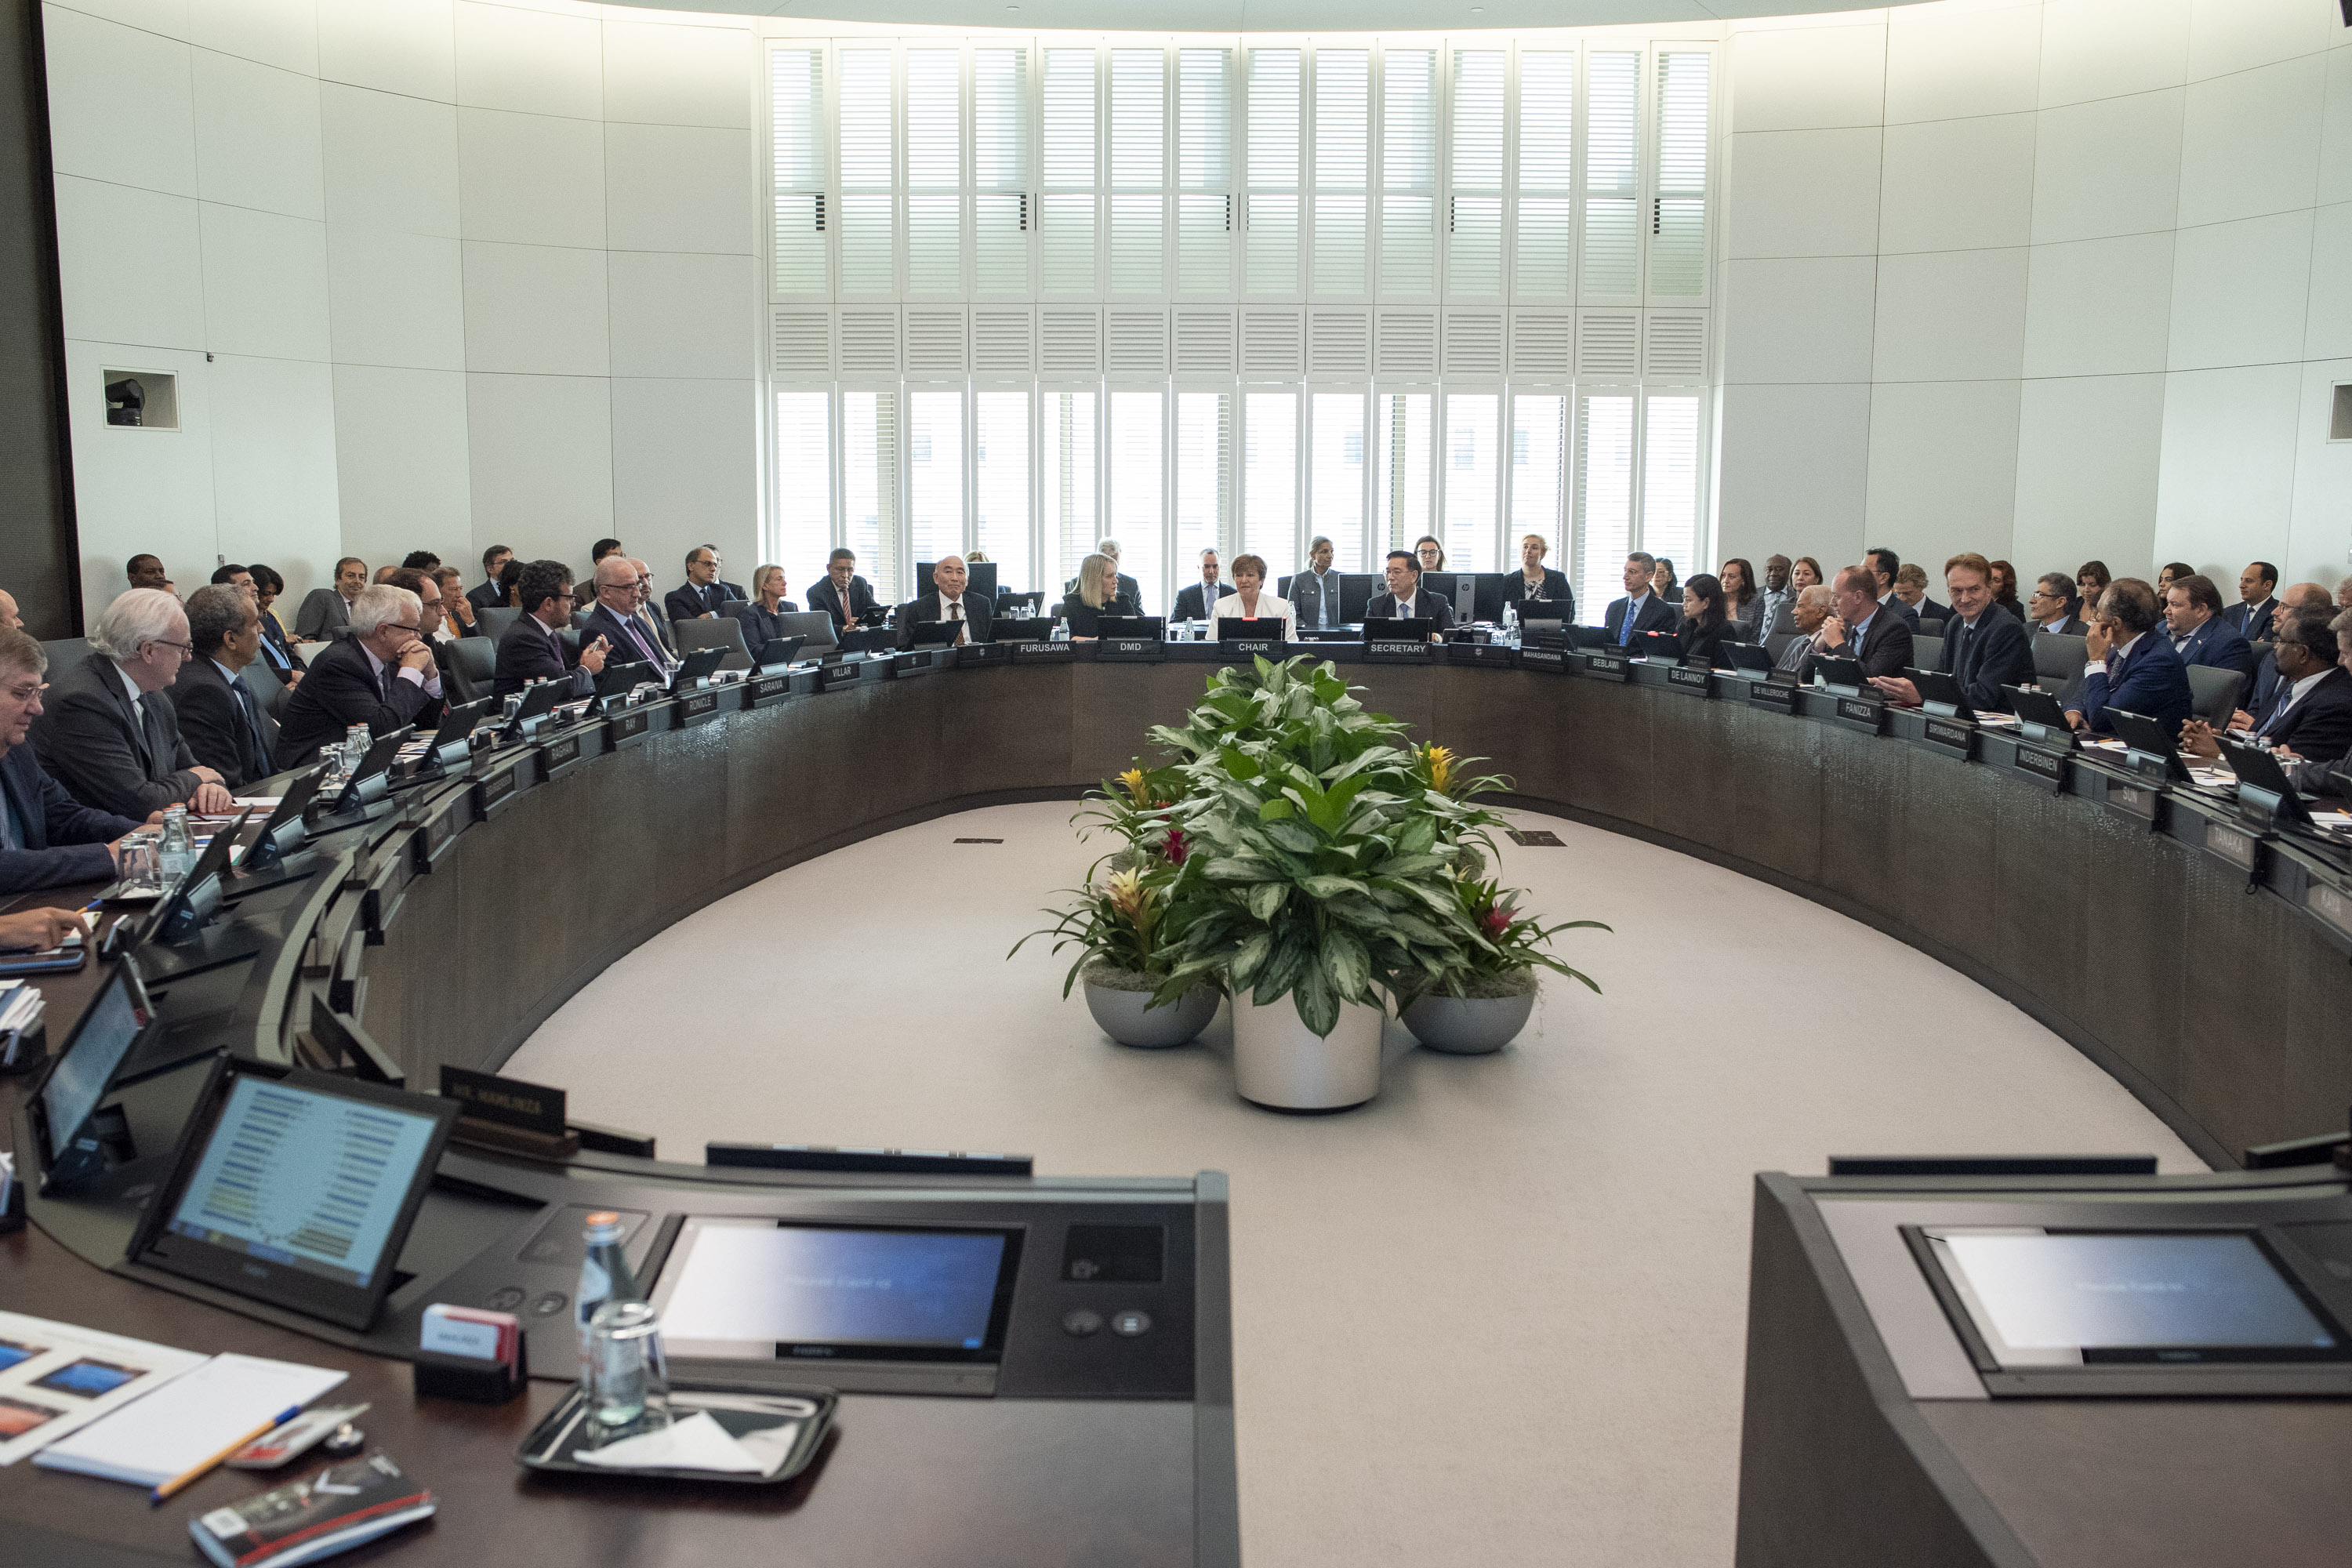
IMF Executive Board Concludes 2019 Article IV Consultation with Kingdom of the Netherlands
IMF News, February 12, 2019
Source details
- Canonical URL
- IMF Executive Board Concludes 2019 Article IV Consultation with Kingdom of the Netherlands
Other formats
Bibliographic details
- Published: February 12, 2019
Overview
- Date: February 12, 2019.
- Growth estimated at 2.6 percent in 2018, driven by strong domestic demand and robust net exports.
- Current account surplus estimated at 9.8 percent of GDP in 2018.
- Unemployment reached a decade low; real wages and inflation remain subdued.
- Households and corporations are deleveraging; credit growth remains negative.
- Banks’ capitalization improved; non-performing loans among the lowest in the euro area.
Economic performance and outlook
- Near-term: Strong domestic demand will support growth as global trade slows.
- Medium- and long-term: Unfavorable demographic developments and weak productivity growth will weigh on potential growth.
- Inflation and wages: Projected to pick up gradually owing to continued labor market tightening and increased basic VAT.
- Fiscal policy: Will remain supportive; public debt is projected to decline further.
Risks to the outlook
- Downside-tilted risks include:
- Rising global protectionism and threats to global demand.
- Uncertainties surrounding fiscal policies in other euro area countries.
- A possible no-agreement Brexit.
- Sharp tightening of global financial conditions, which could:
- Weigh on highly leveraged households with large balance sheets.
- Increase volatility of the economy and reduce consumption.
- Heighten stress in banks due to heavy reliance on wholesale funding.
Executive Board Assessment and recommendations
- Directors’ summary:
- Commended sound macroeconomic management and robust economic performance increasingly driven by domestic demand.
- Noted growth rates above the euro area average, a strong fiscal position, low unemployment, and a generally healthy banking sector.
- Highlighted structural imbalances in household and corporate sectors and external uncertainties that weigh on medium-term potential growth.
- Priority policy areas recommended by Directors:
- Address imbalances by boosting household disposable income and reducing household debt.
- Strengthen the small and medium‑sized enterprises (SMEs) sector to support long‑term growth and resilience.
- Use the economic upswing to build fiscal buffers; many Directors recommended:
- Further reducing labor taxation.
- Increasing spending on priorities such as human capital and research and development (R&D).
- Preserving some fiscal space as a buffer against adverse shocks.
- Encourage higher wage growth and welcome planned decrease in the labor tax wedge.
- Reduce labor market duality; part‑time workers and the self‑employed have on average lower wages.
- Pension system reform that provides more choice could reduce prevalence of self‑employment and support higher wages.
- Improve housing affordability and reduce household indebtedness:
- Lower mortgage interest deductibility to reduce mortgage debt bias.
- Further tighten macroprudential policies, including loan‑to value and debt‑service‑to‑income ratios.
- Further liberalize rent controls, improve mean‑testing for social housing, and simplify building permit procedures to boost housing supply.
- Improve coordination among main stakeholders.
- Support SMEs and boost investment:
- Expand direct public support to R&D.
- Increase access to finance for SMEs; consider establishing a credit bureau to improve information availability and access to finance.
- Financial sector:
- Continue building buffers and strengthen supervision given banks remain highly leveraged, concentrated, and vulnerable to shocks.
- Maintain a strong AML/CFT framework given the Netherlands’ position as a financial and corporate center.
Key economic indicators (2017–2020)
- National accounts (percent change)
- Gross domestic product: 2017 = 2.9; 2018 = 2.6; 2019 = 2.2; 2020 = 2.1
- Private consumption: 2017 = 1.9; 2018 = 2.4
- Public consumption: 2017 = 1.1; 2018 = 1.4; 2019 = 1.8; 2020 = 2.0
- Gross fixed investment: 2017 = 6.1; 2018 = 4.9; 2019 = 4.7; 2020 = 4.5
- Total domestic demand: 2017 = 2.7; 2018 = 2.8
- Exports of goods and nonfactor services: 2017 = 5.4; 2018 = 5.1; 2019 = 4.4; 2020 = 3.9
- Imports of goods and nonfactor services: 2017 = 5.5; 2018 = 5.3
- Net foreign balance¹: 2017 = 0.9; 2018 = 0.2; 2019 = -0.3; 2020 = -0.4
- Output gap (percent of potential output): 2017 = -0.1; 2018 = 0.7; 2019 = 1.2
- Prices, wages, and employment
- Consumer price index (HICP): 2017 = 1.3; 2018 = 1.6
- GDP deflator: 2017 = 2.3
- Hourly compensation (manufacturing): 2017 = 2.5; 2018 = 3.0
- Unit labor costs (manufacturing): 2017 = -1.5; 2018 = 0.0; 2019 = 0.1; 2020 = 0.4
- Employment (percent) — Unemployment rate (national definition): 2017 = 5.9
- Unemployment rate (ILO definition): 2017 = 3.8; 2018 = 3.7
- NAIRU: 2017 = 5.2
- External trade
- Merchandise balance (percent of GDP): 2017 = 9.6; 2018 = 9.1; 2019 = 8.6; 2020 = 8.0
- Current account balance (percent of GDP): 2017 = 10.5; 2018 = 9.8; 2019 = 9.5; 2020 = 8.9
- General government accounts (percent of GDP)
- Revenue: 2017 = 43.7; 2018 = 43.6; 2019 = 44.0
- Expenditure: 2017 = 42.6; 2018 = 42.5; 2019 = 43.0; 2020 = 42.8
- Net lending/borrowing: 2017 = 1.0; 2018 = 0.8
- Primary balance: (not specified numerically in table)
- Structural balance²: 2017 = 0.5
- Structural primary balance²: 2017 = 1.5
- General government gross debt: 2017 = 57.0; 2018 = 54.6; 2019 = 51.6; 2020 = 49.1
IMF Executive Board Concludes 2019 Article IV Consultation with Kingdom of the Netherlands, February 12, 2019.