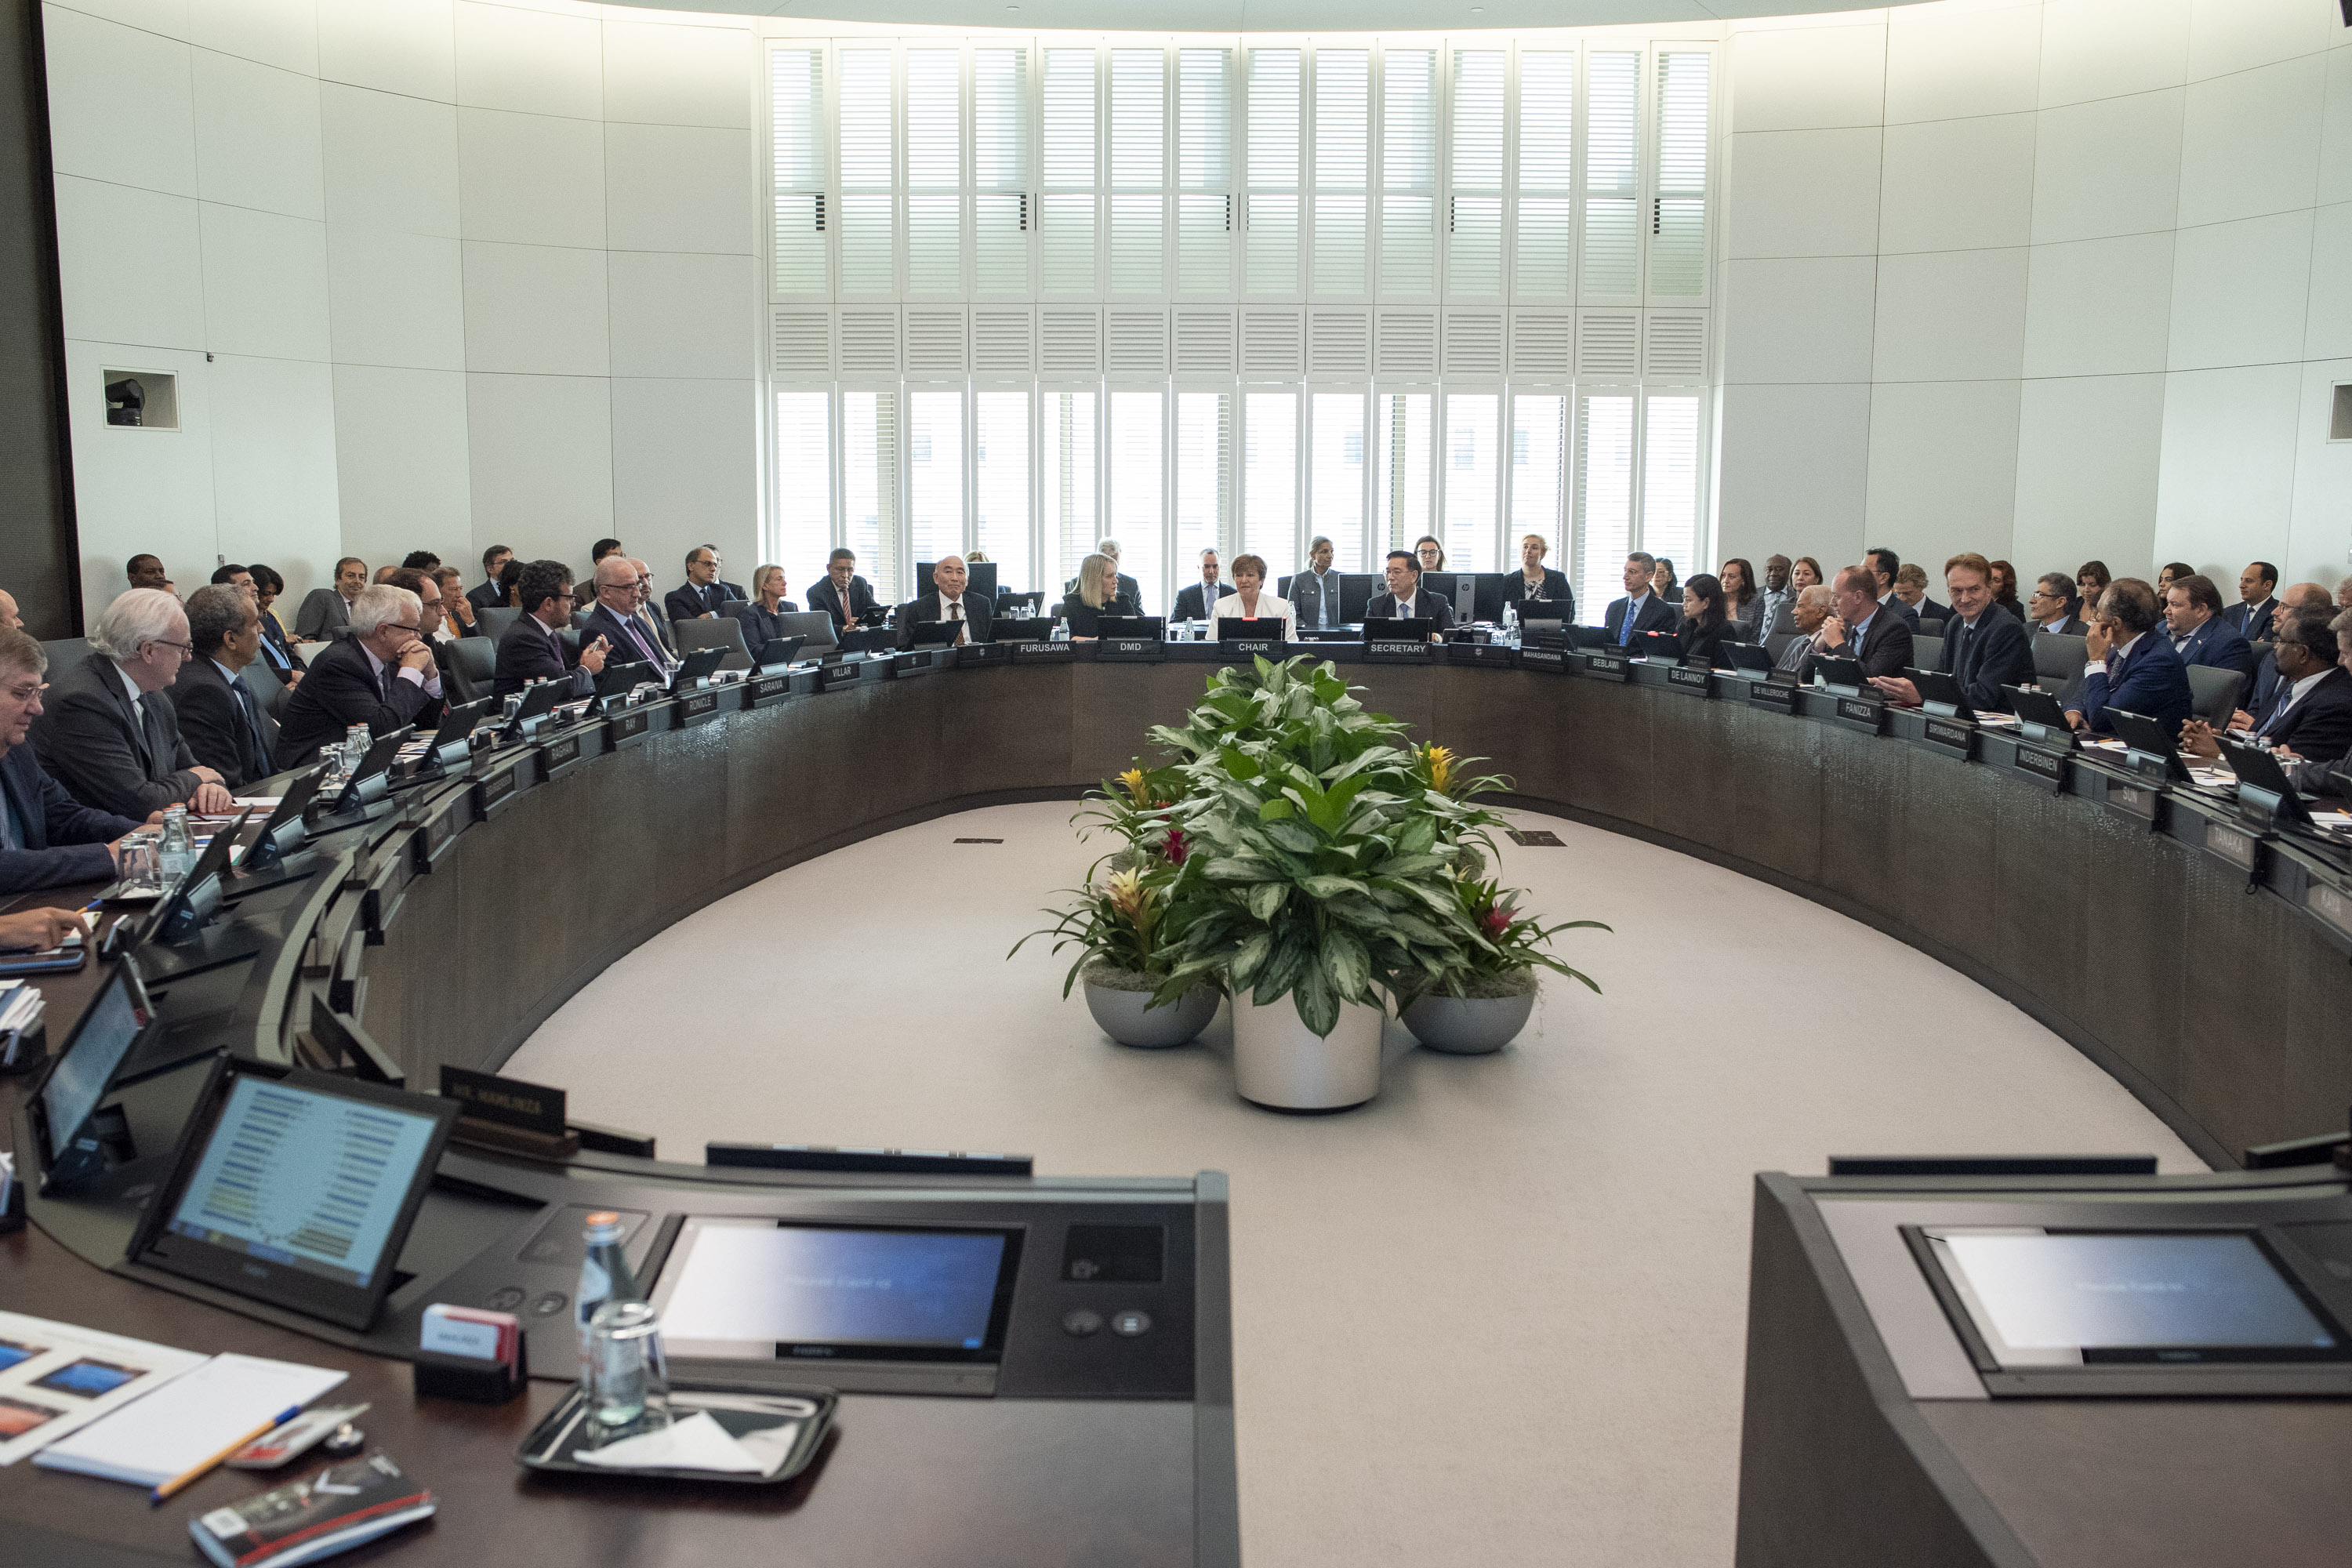
IMF Executive Board Concludes 2019 Article IV Consultation with the Republic of Korea
IMF News, May 13, 2019
Source details
- Canonical URL
- IMF Executive Board Concludes 2019 Article IV Consultation with the Republic of Korea
Other formats
Bibliographic details
- Published: May 13, 2019
Overview and Context
- On May 8, 2019, the Executive Board of the International Monetary Fund (IMF) concluded the Article IV consultation with the Republic of Korea.
- Korea’s economy has strong fundamentals and a resilient financial system, but short-term growth is moderating amid cyclical and structural headwinds, with risks to the downside.
- Key structural concerns include unfavorable demographics, slowing productivity growth, rising household leverage, weak domestic demand, income inequality and polarization, and labor and product market duality.
Growth Performance and Projections
- Real GDP (percent change)
- 2017: 3.1
- 2018: 2.7
- 2019 (projection): 2.6
- 2020 (projection): 2.8
- Drivers of the 2018 slowdown:
- Global slowdown in trade and in demand and prices for semi-conductors.
- Weakened export growth due to trade tensions and China’s growth slowdown.
- Equipment investment affected; employment growth fell to 0.4 in 2018 from 1.2 percent in 2017.
- Outlook for 2019:
- Growth projected to slide to around 2.6 percent in 2019.
- Deterioration in external demand expected to drive the slowdown.
- Domestic consumption expected to accelerate, supported by fiscal stimulus embedded in the 2019 budget and a supplementary budget.
- Facility investment expected to face continued headwinds; construction investment expected to stabilize closer to long-term trends.
- Economic slack will dissipate only gradually.
Inflation, Labor Market, and Social Policies
- Inflation
- Year-on-year headline inflation declined to 0.5 percent in February 2019.
- Core inflation excluding food and energy recorded 1.1 percent year-on-year in February 2019.
- Labor market
- Employment growth: 1.2 percent in 2017; 0.4 in 2018.
- Weak job creation by the private sector noted.
- Social and labor measures taken by authorities
- Strengthened social safety nets.
- Substantially raised the minimum wage.
- Supported SMEs to boost employment.
- Expanded public sector jobs.
- Structural issues emphasized: income equality and polarization worsening; need to address labor market duality.
External Sector, Savings, and Investment
- Current account and saving
- Current account balance (percent of GDP): 4.9 in 2017; 4.6 in 2018.
- Gross national saving (percent of GDP): 36.0 in 2017; 34.9 in 2018; 34.2 (2019 proj.); 33.7 (2020 proj.).
- Gross domestic investment (percent of GDP): 31.1 in 2017; 30.2 in 2018; 29.6 (2019 proj.); 29.3 (2020 proj.).
- Trade volumes (percent change)
- Export volume: 5.3 in 2017; 7.2 in 2018.
- Import volume: 8.5 in 2017; 3.0 in 2018; 2.9 (2019 proj.).
- Terms of trade: -0.8 in 2017; -6.5 in 2018.
- Nominal GDP (in trillions of won)
- 2017: 1,730.4
- 2018: 1,782.3
- 2019 (proj.): 1,852.8
- 2020 (proj.): 1,937.0
Fiscal and Monetary Policy Stance
- Fiscal policy
- Fiscal stance was tight in 2018.
- Structural budget surplus estimated to have increased by 0.4 percentage point compared to 2017, to 2.9 percent of GDP.
- Consolidated central government (in percent of GDP) — Revenue: 23.2 (2017); 24.2 (2018); 24.7 (2019 proj.); Expenditure: 20.8 (2017); 21.5 (2018); 22.7 (2019 proj.); 23.1 (2020 proj.).
- Net lending/borrowing and balances: Overall balance 0.6 (2017). Excluding Social Security Funds: -1.1 (2017); -0.6 (2018); -1.4 (2019 proj.).
- Directors noted Korea has ample fiscal space and generally concurred that fiscal policy should remain expansionary into the medium term to support growth, job creation, and external rebalancing.
- Directors welcomed the planned supplementary budget and the authorities’ readiness to take further action as necessary.
- Longer-term recommendation: tax reforms to promote innovation and efficiency and greater revenue mobilization to prepare for the aging population.
- Monetary policy
- Bank of Korea increased its main policy rate by 25 basis points to 1.75 percent in November 2018 and has been on hold since.
- Directors agreed that monetary policy should remain accommodative.
- With inflation projected to remain below target and the output gap negative, most Directors saw room for further easing of monetary policy; a few Directors emphasized preserving policy space and financial stability.
- Encouraged reliance on targeted macroprudential policies to manage financial stability risks, including from high household indebtedness and possible house price corrections.
- Ongoing efforts to strengthen regulatory and oversight frameworks welcomed.
Financial Sector and Risks
- Household and financial risks
- Household leverage keeps increasing, albeit at a slower pace, creating concerns about financial risk.
- Directors encouraged macroprudential measures and welcomed strengthening of regulatory and oversight frameworks.
- External debt and reserves
- Gross international reserves (end of period, in billions of U.S. dollars): 384.5 (2017); 398.9 (2018); 422.2 (2019 proj.); 444.5 (2020 proj.).
- In percent of short-term debt (residual maturity): 227.2 (2017); 226.8 (2018); 232.8 (2019 proj.); 237.9 (2020 proj.).
- Total external debt (end of period, in billions of U.S. dollars): 412.0 (2017); 440.6 (2018); 489.0 (2019 proj.); 531.2 (2020 proj.).
- Short-term external debt (end of period, in billions of U.S. dollars): 116.0 (2017); 126.6 (2018); 128.1 (2019 proj.); 133.5 (2020 proj.).
- Total external debt (in percent of GDP): 26.9 (2017); 27.2 (2018); 29.5 (2019 proj.); 30.5 (2020 proj.).
- Debt service ratio: 8.2 (2017); 8.8 (2018); 9.8 (2019 proj.); 10.9 (2020 proj.).
Structural Reforms and Policy Recommendations
- Promote balanced, private sector-led growth, foster inclusion, and enhance productivity.
- Fiscal policy
- Remain expansionary into the medium term.
- Use fiscal policy to promote women and youth employment, enhance active labor market policies, and support growth-enhancing structural reforms.
- Undertake tax reforms to promote innovation and efficiency in resource allocation.
- Mobilize greater revenue to prepare for an aging population.
- Monetary and macroprudential policy
- Keep monetary policy accommodative given below-target inflation and a negative output gap; most Directors saw room for further easing.
- Rely more on targeted macroprudential policies to manage financial stability risks from high household indebtedness and house price corrections.
- Labor and product market reforms
- Enhance flexibility and security (flexicurity) in the labor market to mitigate duality and create private-sector jobs.
- Link minimum wage increases to labor productivity growth and phase out compensatory subsidies to small- and medium-sized enterprises.
- Diversify the manufacturing sector and liberalize the services sector by easing regulatory burdens, lowering barriers to entry, and reducing protection of existing firms.
- Exchange rate and external rebalancing
- Continue commitment to a flexible exchange rate.
- Policies and structural reforms that promote domestic demand and private investment would help reduce the current account surplus.
Key Selected Economic Indicators (2017–20, projections where indicated)
- Real GDP (percent change): 3.1 (2017); 2.7 (2018); 2.6 (2019); 2.8 (2020).
- Total domestic demand: 5.1 (2017); 1.7 (2018); 3.3 (2019).
- Final domestic demand: 4.7 (2017); 1.6 (2018); 3.9 (2019).
- Consumption (percent change): 3.5 (2017); 3.6 (2018).
- Gross fixed investment: 8.6 (2017); -2.2 (2018); 0.7 (2019); 4.5 (2020).
- Stock building (contribution to GDP growth): 0.4 (2017); 0.1 (2018); 0.2 (2019); -0.5 (2020).
- Net foreign balance (contribution to GDP growth): -1.7 (2017); 1.2 (2018); -0.4 (2019); -0.3 (2020).
- CPI inflation (end of period): 1.4 (2017); 1.3 (2018).
- CPI inflation (average): 1.9 (2017); 1.5 (2018).
- GDP deflator: 2.3 (2017); 0.3 (2018).
- Real effective exchange rate: 0.9 (2018).
- Exports, f.o.b. (billions of U.S. dollars): 580.3 (2017); 625.4 (2018); 638.5 (2019 proj.); 660.3 (2020 proj.).
- Imports, f.o.b. (billions of U.S. dollars): 466.7 (2017); 513.6 (2018); 523.4 (2019 proj.); 538.9 (2020 proj.).
- Oil imports (billions of U.S. dollars): 59.6 (2017); 80.4 (2018); 69.8 (2019 proj.); 71.9 (2020 proj.).
- M3 growth (end of period): 6.6 (2018).
- Overnight call rate, Three-year AA- corporate bond yield: (listed in indicators without numeric values in the source).
IMF Communications Department — Press Release No. 19/161, May 13, 2019.