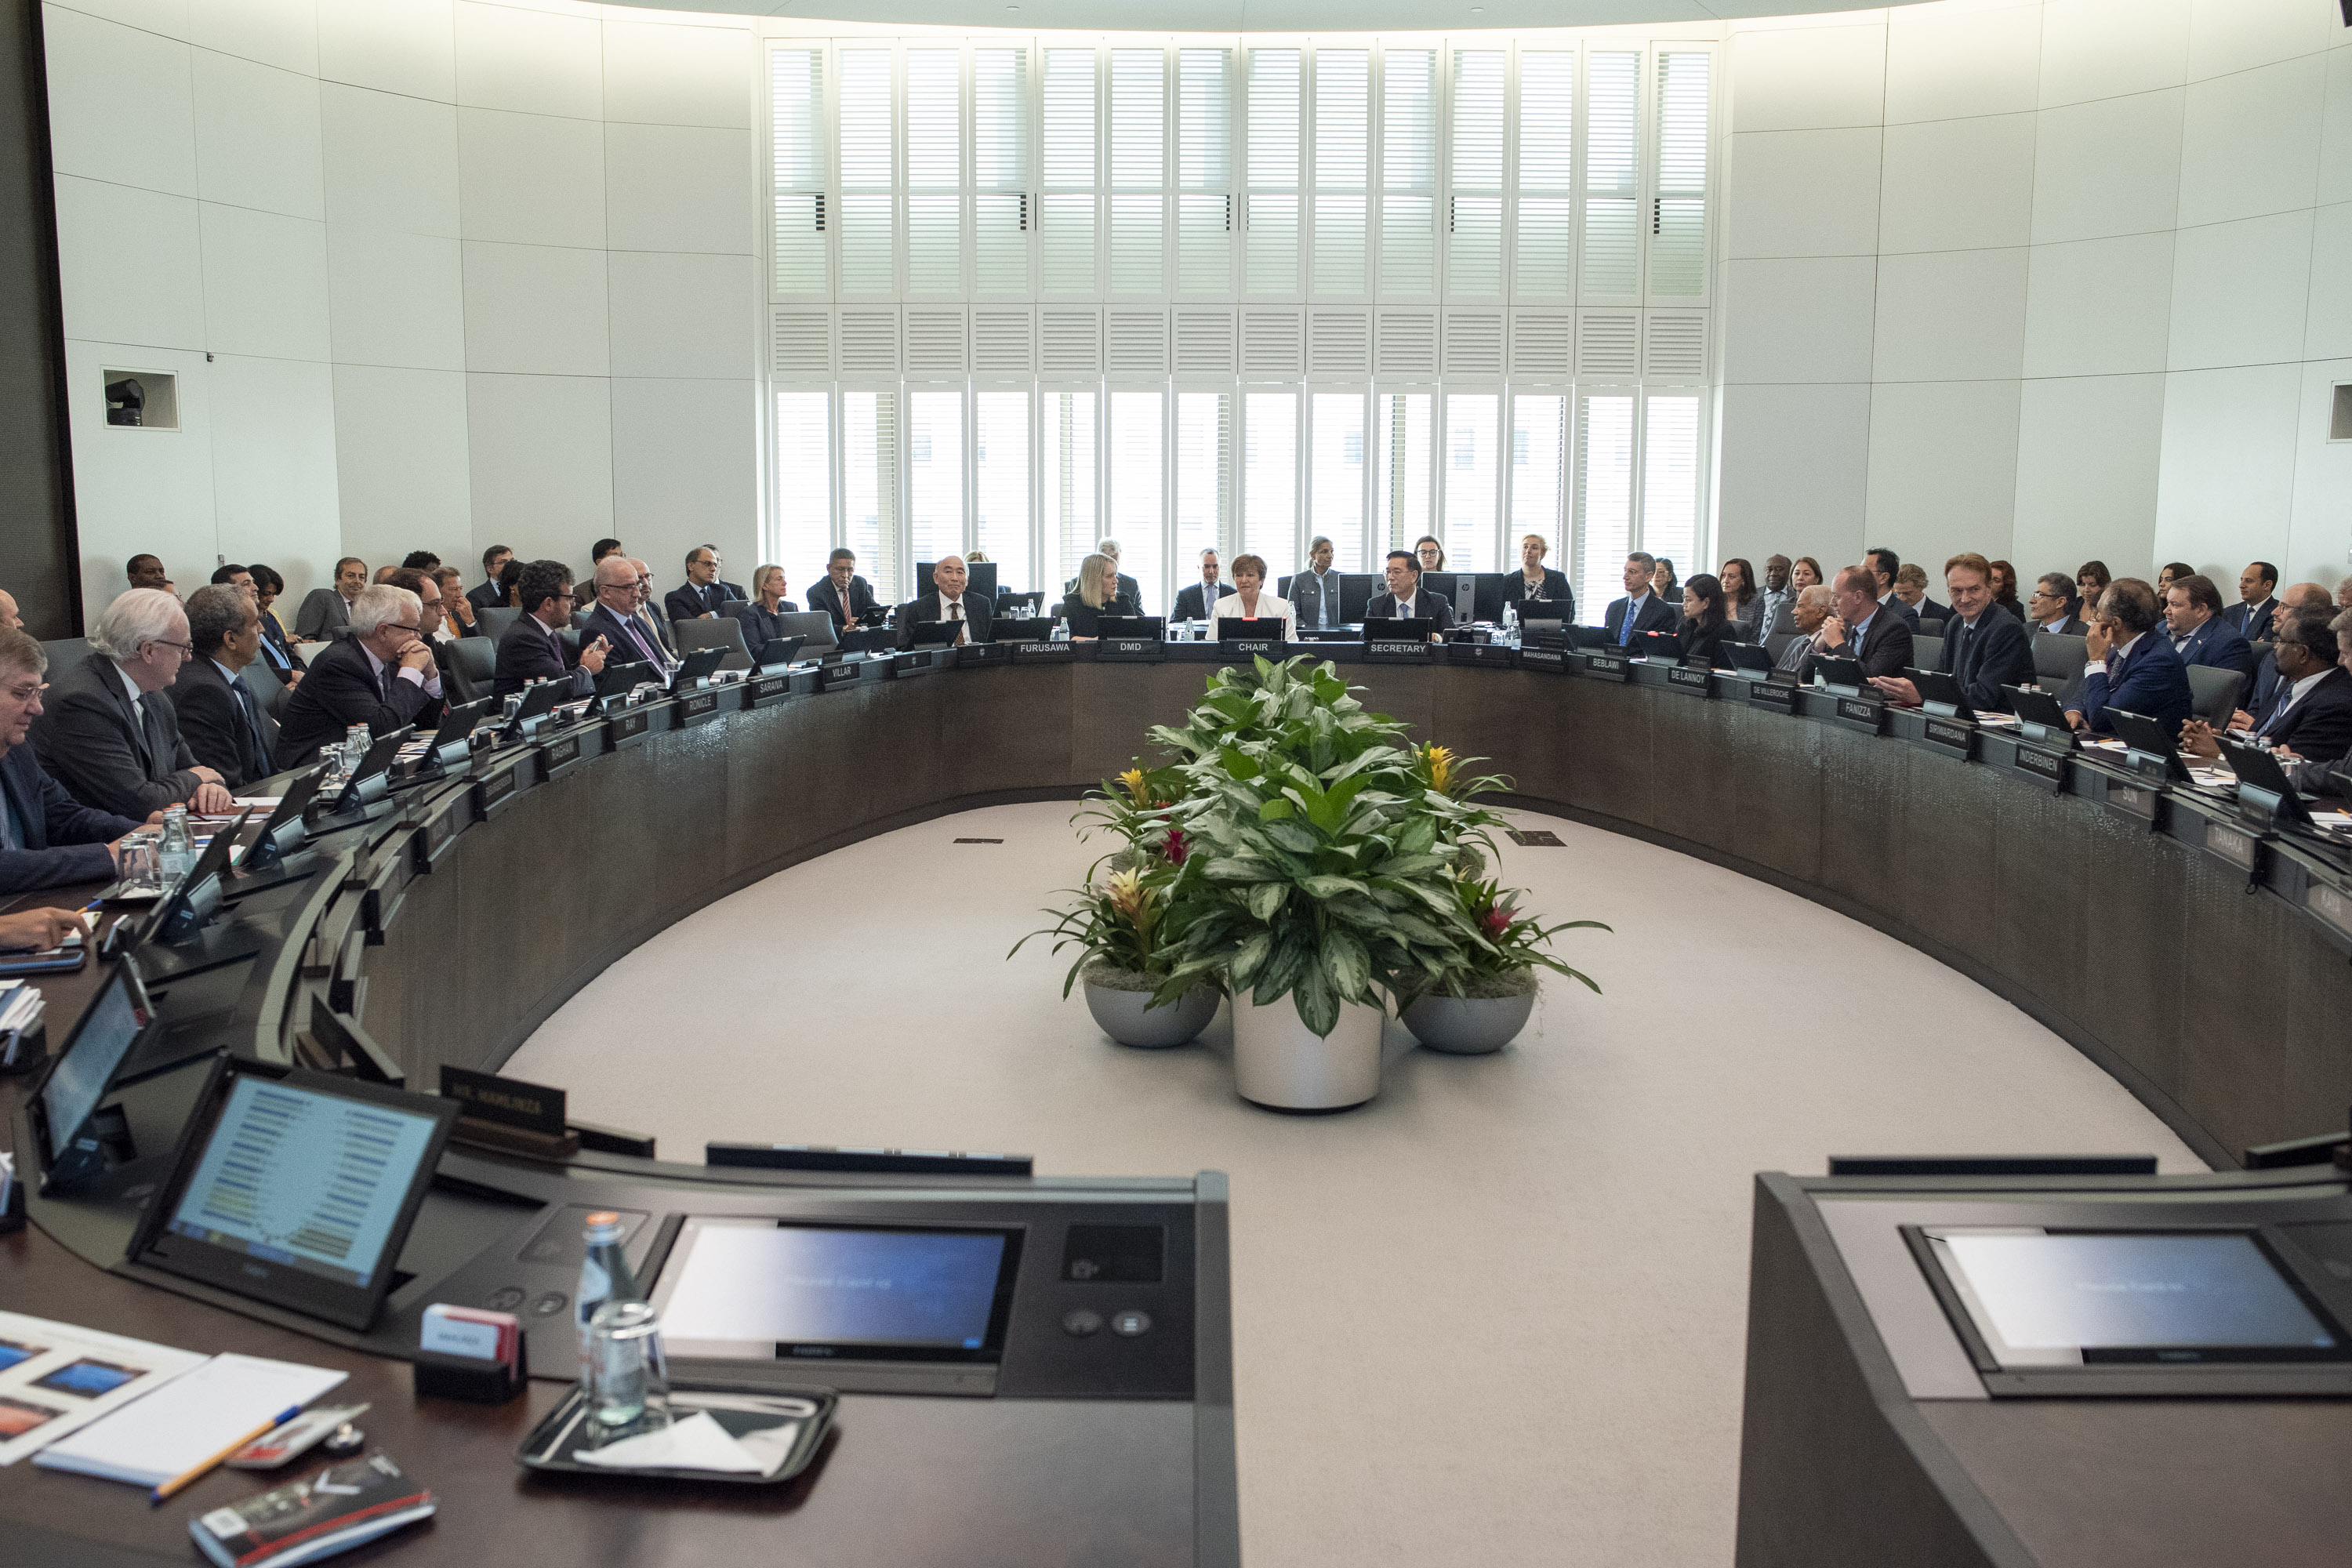
IMF Executive Board Approves a US$152.61 Million Disbursement Under the Rapid Financing Instrument to Gabon to Address the COVID-19 Pandemic
IMF News, July 31, 2020
Source details
- Canonical URL
- IMF Executive Board Approves a US$152.61 Million Disbursement Under the Rapid Financing Instrument to Gabon to Address the COVID-19 Pandemic
Other formats
Bibliographic details
- Published: July 31, 2020
Disbursement and Purpose
- The Executive Board approved a purchase of SDR108 million (about US$152.61 million) under the Rapid Financing Instrument (RFI).
- This is the second purchase under the RFI to Gabon since the onset of the pandemic.
- Today's purchase brings total IMF COVID-19 support under the RFI to Gabon to US$299.61 million.
- The RFI resources aim to help Gabon meet urgent balance of payments needs and to:
- boost healthcare,
- protect the most vulnerable,
- support the private sector, notably small businesses.
Economic Context and Impact of COVID-19
- Since the first RFI purchase on April 9, 2020, weaker external demand and a more pronounced impact of containment measures have further deteriorated growth prospects and worsened external and fiscal positions.
- Lower domestic activity, crisis-related measures affecting non-oil government revenue and spending, and losses in oil revenue have placed significant pressures on public finances and public debt.
- The authorities adopted a revised budget with a larger deficit to accommodate automatic stabilizers and crisis-related emergency spending.
- The authorities are taking steps to ensure proper use of COVID-19 emergency resources, including:
- an ex-post audit of crisis-related spending,
- publication of all crisis-related procurement contracts.
IMF Assessment and Statement by the Chair
- Mr. Mitsuhiro Furusawa, Deputy Managing Director and Chair, summarized the Executive Board discussion with key points:
- The dual COVID-19 pandemic and terms of trade shocks continue to severely affect human conditions and hamper growth prospects in Gabon.
- The economic contraction has deepened since the first RFI request in April 2020, and external and fiscal positions have worsened, giving rise to additional financing needs.
- Public debt remains sustainable, but downside risks have increased significantly.
- The near-term outlook remains subject to considerable uncertainty and downside risks.
- The authorities’ measures to limit the spread of COVID-19 while safeguarding debt sustainability and improving reporting are commendable.
- A package of monetary easing measures was approved by the regional central bank.
- The IMF emergency assistance will support the authorities’ policy response and catalyze donor support.
- Contingency planning and close monitoring of financial sector vulnerabilities remain critical to preserve macroeconomic stability.
- The authorities’ commitment to promote strong and inclusive growth over the medium term is welcome.
Policy Recommendations and Priorities Highlighted
- Safeguard debt sustainability while responding to the pandemic.
- Improve transparency and public financial management to ensure proper use of emergency resources.
- Continue contingency planning and close monitoring of financial sector vulnerabilities.
- Pursue measures to:
- achieve a more revenue-based and growth-friendly fiscal consolidation,
- enhance governance and debt management,
- improve the business climate,
- put public debt on a firmly downward path and help sustain strong and inclusive growth.
Key Statistics (Selected)
- Population (2017, UN est.): 2.01 million
- Per capita GDP (2017): US$ 7,490
- Quota: SDR 216.0 million
- Literacy rate (2012): 82.3 percent
- Poverty rate (2017): 32.4 percent
- Main products and exports: Crude petroleum; Manganese ore.
- Key export markets: China; European Union, Australia
Macroeconomic Indicators (Selected values by year)
- Real GDP (Output, Percent)
- 2016: 2.1
- 2017: 0.5
- 2018: 1.0
- 2019: 3.8
- 2020 Est.: -2.7
- 2021 Proj.: (no value provided in table for Real GDP 2021)
- Non-oil GDP (Percent)
- 2016: 3.3
- 2017: 2.5
- 2018: 1.7
- 2019: 3.2
- 2020 Est.: -0.1
- 2021 Proj.: 2.3
- Inflation (End of period, Percent)
- 2016: 4.1
- 2017: 1.1
- 2018: 6.3
- 2019: 3.0
- Inflation (Average, Percent)
- 2016: 2.7
- 2017: 4.8
- 2018: 2.0
- 2019: (no value provided)
- Central Government Finances (Percent of GDP)
- Revenue:
- 2016: 17.1
- 2017: 16.4
- 2018: 16.9
- 2019: 19.5
- 2020 Est.: 15.5
- 2021 Proj.: 15.8
- Expenditure and net lending:
- 2016: 22.1
- 2017: 19.0
- 2018: 18.2
- 2019: 20.9
- 2020 Est.: 19.2
- 2021 Proj.: (no value provided)
- Fiscal Balance (cash basis):
- 2016: -6.6
- 2017: -3.4
- 2018: -1.6
- 2019: 0.8
- 2020 Est.: -5.4
- 2021 Proj.: -3.5
- Total Public Debt:
- 2016: 64.2
- 2017: 62.9
- 2018: 60.6
- 2019: 58.7
- 2020 Est.: 74.7
- 2021 Proj.: 74.4
- Central Government Finances (Percent of Non-oil GDP)
- Revenue and grants:
- 2016: 24.2
- 2017: 23.6
- 2018: 25.0
- 2019: 29.0
- 2020 Est.: 20.4
- 2021 Proj.: 20.8
- Oil:
- 2016: 7.2
- 2017: 9.5
- 2018: 9.2
- 2019: 11.2
- 2020 Est.: 5.9
- 2021 Proj.: 5.8
- Non-oil:
- 2016: 17.0
- 2017: 14.1
- 2018: 17.8
- 2019: 14.2
- 2020 Est.: 15.0
- 2021 Proj.: 31.2
- o/w Current:
- 2016: 27.4
- 2017: 26.9
- 2018: 27.0
- 2019: 27.6
- 2020 Est.: 25.3
- o/w Capital:
- 2016: (no value provided)
- 2017: (no value provided)
- 2018: 6.9
- 2019: 2.2
- 2020 Est.: 3.9
- 2021 Proj.: 4.2
- Non-oil primary balance:
- 2016: -11.0
- 2017: -9.7
- 2018: -7.6
- 2019: -5.8
- 2020 Est.: -8.9
- 2021 Proj.: -6.4
- Basic non-oil primary balance 1/ (Excludes externally-financed capital expenditures)
- 2016: -6.9
- 2017: -8.6
- 2018: -5.0
- 2019: -4.2
- 2020 Est.: -5.7
- Money and Credit
- Broad Money (Percentage change):
- 2016: -5.2
- 2017: -3.9
- 2018: 15.7
- 2019: 1.2
- 2020 Est.: 5.0
- 2021 Proj.: 10.0
- Credit to the private sector (Percentage change):
- 2016: -5.6
- 2017: -3.0
- 2018: 6.2
- 2019: -6.5
- 2020 Est.: 3.1
- Balance of Payments
- Current account (Percent of GDP):
- 2016: -10.4
- 2017: -7.0
- 2018: -3.2
- 2019: -0.3
- 2020 Est.: -9.5
- 2021 Proj.: -6.3
- FDI (Percent of Non-oil GDP):
- 2016: 6.5
- 2017: 7.6
- 2018: 7.3
- 2019: 7.7
- 2020 Est.: 7.8
- CEMAC Foreign Reserves (months of extrazone imports):
- 2016: 2.4
- 2017: 2.8
- 2018: 3.4
- 2019: 3.5
- External Debt (Percent of GDP):
- 2016: 37.4
- 2017: 38.7
- 2018: 40.0
- 2019: 39.2
- 2020 Est.: 50.6
- 2021 Proj.: 53.5
Source: IMF Press Release No. 20/276, July 31, 2020.
References
- https://www.imf.org/-/media/images/imf/bios/imfboard.jpg
- The Executive Board
- Gabon and the IMF
- IMF Borrowing Arrangements: GAB and NAB -- A Factsheet
- Press Releases
- PRESS CENTER
- see IMF Policy Paper No. 20/018
- see IMF Country Report No 20/109
- https://www.imf.org/en/Topics/imf-and-covid19/COVID-Lending-Tracker
- https://www.imf.org/external/NP/SEC/bc/eng/index.aspx
- https://www.imf.org/en/home