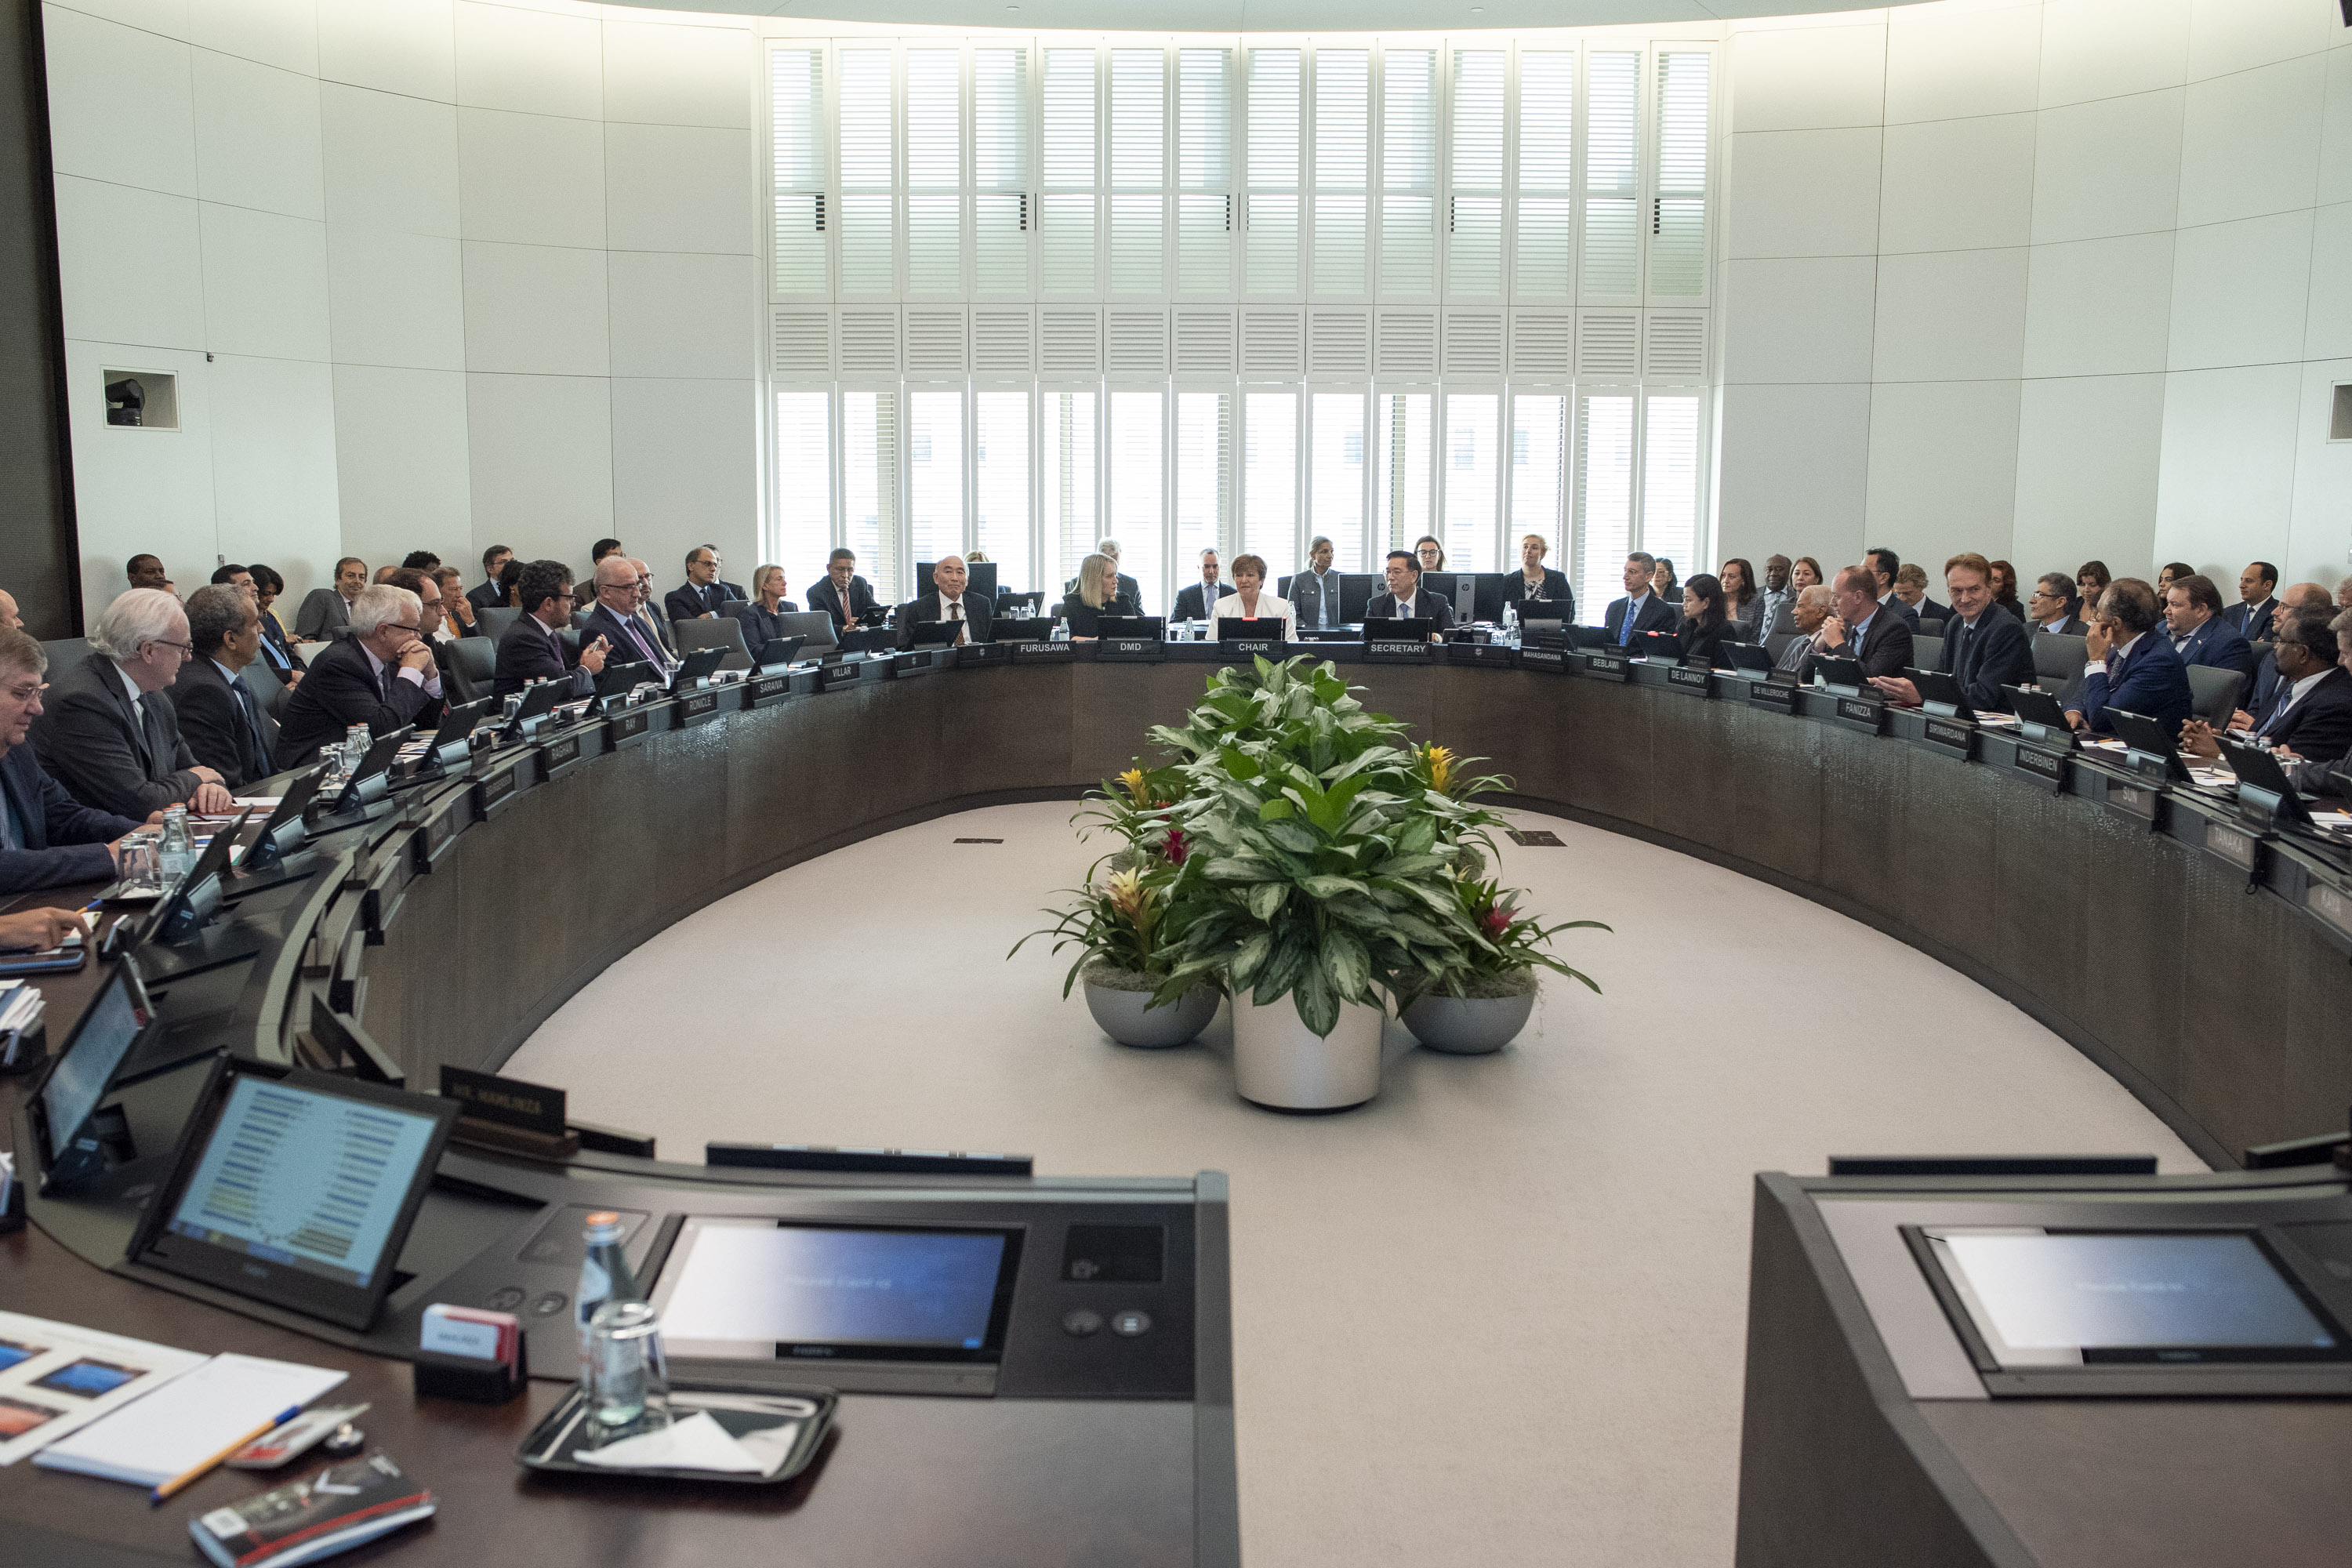
IMF Executive Board Completes the Sixth Review under the Extended Credit Facility Arrangement and the Second Review under the Resilience and Sustainability Facility Arrangement, and Concludes the 2024 Article IV Consultation with Niger
IMF News, January 22, 2025
Source details
- Canonical URL
- IMF Executive Board Completes the Sixth Review under the Extended Credit Facility Arrangement and the Second Review under the Resilience and Sustainability Facility Arrangement, and Concludes the 2024 Article IV Consultation with Niger
Other formats
Bibliographic details
- Published: January 22, 2025
Immediate disbursements and program financing
- Immediate disbursement of about US$51 million cumulatively under the ECF and the RSF.
- ECF disbursement for the review: SDR 13.16 million (about US$17 million); total disbursements under the ECF arrangement to date: SDR 171.08 million (about US$ 227 million).
- RSF disbursement for the review: SDR 25.662 million (about US$34 million); total disbursements under the RSF arrangement to date: SDR 59.88 million (about US$78 million).
Growth outlook and macroeconomic projections
- GDP growth estimated at 8.8 percent in 2024 (driven by oil production).
- GDP growth projected at 7.9 percent in 2025 (driven by oil exports at full capacity and expected normalization of supply chains and cross-border trade activities with Benin).
- Table 1 highlights selected projections (annual percentage change and levels):
- GDP at constant prices: 2023 Est. 2.4; 2024 10.6; 2025 8.8; 2026 7.4; 2027 7.9; 2028 6.7; 2029 6.4; 2030 6.0.
- Export volume: 2023 -13.5; 2024 113.0; 2025 66.9; 2026 52.5; 2027 91.7; 2028 7.2; 2029 0.2; 2030 0.8; 2031 2.3.
- Import volume: 2023 -3.1; 2024 14.7; 2025 4.0; 2026 10.1; 2027 12.0; 2028 6.8; 2029 8.0.
- CPI (annual average): 2023 3.7; 2024 4.4; 2025 9.1; 2026 3.6; 2027 3.2; 2028 2.0.
- CPI (end-of-period): 2023 3.0; 2024 3.1; 2025 4.7; 2026 4.8; 2027 2.5.
- Broad money: 2023 -0.9; 2024 10.5; 2025 14.2; 2026 13.6; 2027 11.7; 2028 8.5; 2029 8.2; 2030 8.1.
- Domestic credit: 2023 25.5; 2024 14.1; 2025 12.3; 2026 6.2.
- Credit to the government (net): 2023 120.6; 2024 74.3; 2025 36.0; 2026 14.8; 2027 18.1; 2028 2.1; 2029 1.7; 2030 -2.0; 2031 -4.4.
- Credit to the private sector: 2023 -6.5; 2024 6.5; 2025 5.7; 2026 11.6; 2027 10.3; 2028 9.5; 2029 8.9.
- Total revenue (percent of GDP): 2023 8.7; 2024 9.4; 2025 8.3; 2026 10.0; 2027 11.2; 2028 11.5.
- Total expenditure and net lending (percent of GDP): 2023 15.8; 2024 16.3; 2025 15.0; 2026 14.6; 2027 15.2; 2028 15.4; 2029 15.5.
- Current expenditure (percent of GDP): 2023 9.6; 2024 9.8; 2025 8.4; 2026 8.6.
- Capital expenditure (percent of GDP): 2023 5.6; 2024 6.1; 2025 6.6.
- Basic balance (excl. grants): 2023 -3.7; 2024 -2.4; 2025 -2.3; 2026 -1.0; 2027 -1.1; 2028 -0.8; 2029 -0.6; 2030 -0.1; 2031 0.1.
- Overall balance (incl. grants): 2023 -5.4; 2024 -4.1; 2025 -3.0.
- Gross investment (percent of GDP): 2023 23.6; 2024 19.3; 2025 17.0; 2026 18.5; 2027 20.5; 2028 19.1; 2029 17.7.
- Non-government investment (percent of GDP): 2023 14.5; 2024 11.9; 2025 13.9; 2026 15.7; 2027 13.5; 2028 12.9; 2029 12.6.
- Government investment (percent of GDP): 2023 4.2; 2024 5.0; 2025 4.6; 2026 5.2; 2027 5.1.
- External current account balance (incl. grants) (percent of GDP): 2023 -13.9; 2024 -7.0; 2025 -4.5; 2026 -4.7; 2027 -4.8.
- External current account balance (excl. grants) (percent of GDP): 2023 -14.8; 2024 -7.1; 2025 -7.4; 2026 -4.6; 2027 -5.0; 2028 -5.2; 2029 -5.3.
- Total public and publicly-guaranteed debt (percent of GDP): 2023 51.9; 2024 48.4; 2025 49.9; 2026 45.6; 2027 44.7; 2028 44.5; 2029 44.4.
- Public and publicly-guaranteed external debt (percent of GDP): 2023 31.6; 2024 28.7; 2025 28.5; 2026 27.6; 2027 27.5; 2028 27.3; 2029 27.7; 2030 28.2.
- NPV of external debt (percent of GDP): 2023 21.8; 2024 18.9; 2025 18.8; 2026 17.9; 2027 17.6; 2028 17.1; 2029 16.6; 2030 16.5; 2031 16.8.
- Public domestic debt (percent of GDP): 2023 20.3; 2024 23.7; 2025 19.9; 2026 22.3; 2027 17.3; 2028 16.7; 2029 16.1.
- GDP at current market prices (Billions of CFA francs): 2023 10,194; 2024 11,718; 2025 11,879; 2026 13,013; 2027 13,305; 2028 14,608; 2029 15,857; 2030 17,146; 2031 18,540.
Risks, debt, and financial sector conditions
- Risks of external and overall debt distress are rated high, though debt remains sustainable over the medium term.
- Downside skew to risks for the outlook.
- Niger continues to experience a funding squeeze with high reliance on costly regional financing; roll-over risks for domestic debt are particularly elevated.
- Banking sector: liquidity pressures and increased financial stability risks.
- Border with Benin remains closed (noted as a constraint to trade normalization).
- Fiscal deficit expected to narrow to 3 percent of GDP by 2025, but funding and liquidity constraints persist.
Program performance and structural reforms
- ECF arrangement performance through end-September: mixed.
- Performance criteria (PCs): 2 out of 3 met.
- Indicative targets (ITs): 2 out of 6 met.
- RSF arrangement: all three reform measures (RMs) for this review were implemented.
- Significant progress noted on structural benchmarks:
- Integration of the Solidarity Fund for the Safeguarding of the Homeland (FSSP) into the 2025 budget.
- Adoption of an oil revenue management strategy.
- Revision of the General Tax Code (CGI).
Executive Board assessment, key priorities and recommendations
- Directors broadly agreed with the staff appraisal: near-term strong recovery but significant challenges and downside risks remain.
- Key priorities emphasized by Directors:
- Revenue-based fiscal consolidation to create fiscal space while maintaining debt sustainability.
- Steadfast progress to mobilize domestic revenues and adopt a framework for oil revenue management.
- Improve quality and efficiency of public spending, including more targeted support to vulnerable groups.
- Maintain a prudent debt policy supported by a zero ceiling on non-concessional external debt.
- Strong implementation of the revised arrears clearance plan to rebuild public trust and support recovery.
- Implement measures to address financial sector vulnerabilities and promote financial inclusion, including:
- Swiftly clear domestic debt service arrears.
- Address payment delays to public sector suppliers.
- Implement bank recapitalization plans to strengthen balance sheets.
- Enhance governance, anti-corruption efforts, and public financial management, including:
- Ensure independence of the Supreme Audit Institution.
- Publish the Fund’s Governance Diagnostic Report.
- Strengthen AML/CFT frameworks.
- Reforms to improve the investment climate and foster private sector development.
- Continue capacity development and overcome barriers to accessing climate finance to support RSF reforms and their rollout.
Institutional context and next steps
- The ECF arrangement was approved on December 8, 2021; the RSF arrangement complemented the ECF in July 2023.
- The next Article IV Consultation is expected to take place in accordance with the Executive Board decision on consultation cycles for members with Fund arrangements.
Source: IMF Press Release No. 25/014, January 22, 2025.
References
- https://www.imf.org/-/media/images/imf/bios/imfboard.jpg
- The Executive Board
- PRESS CENTER
- Benin and the IMF
- Niger and the IMF
- IMF Policy Advice -- A Factsheet
- IMF-World Bank Debt Sustainability Framework for Low-Income Countries -- A Factsheet
- Special Drawing Rights (SDRs) -- A Factsheet
- Press Releases
- PR 21/366
- PR 23/256
- https://www.imf.org/en/home