More Action Needed to Resolve Problem Loans in the Caribbean
IMF Blog, October 31, 2017
Source details
- Canonical URL
- More Action Needed to Resolve Problem Loans in the Caribbean
Other formats
Bibliographic details
- Authors: Kimberly Beaton, Inci Otker
- Published: October 31, 2017
Extent and nature of the problem
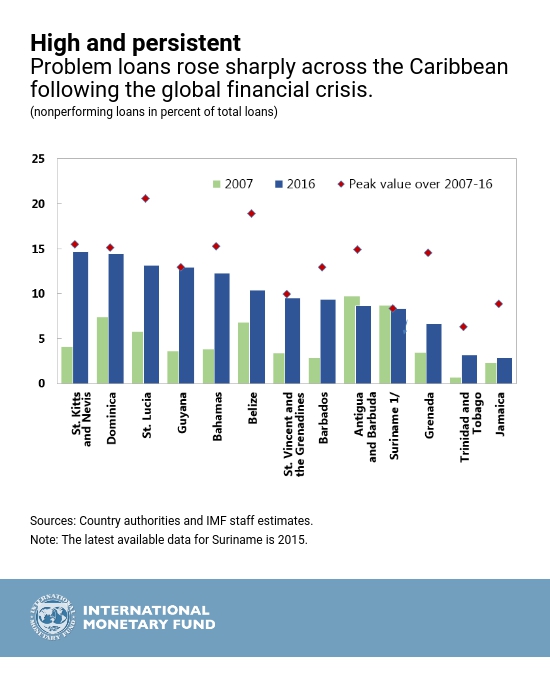
- The share of nonperforming loans to total loans more than tripled in many Caribbean countries from 2007 to 2016.
- Nonperforming loans are defined as loans that are 90 days or more past due.
- The share of nonperforming loans in total loans peaked between 15–20 percent—up from a pre-crisis average of 5 percent and compared to 3–4 percent in Latin America.
- Banks on average resolved only 16 percent of nonperforming loans in their portfolios in 2013-2015.
- Problem loans are concentrated mainly in personal, construction, and tourism loans.
Economic and financial consequences
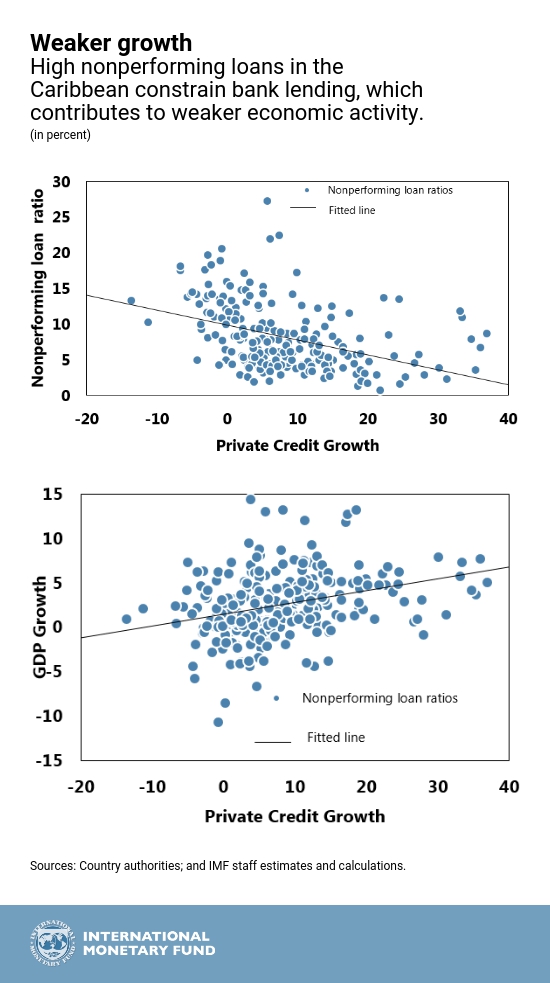
- High nonperforming loans constrain the availability of credit as banks tighten lending standards and focus on cleaning up balance sheets.
- The decline in bank lending from worsening asset quality can persist, with effects lasting up to five years.
- Limited access to credit threatens investment and durable growth in the region.
- High nonperforming loans raise banks’ borrowing costs and reduce profitability, increasing vulnerability to shocks and posing potential risk to financial stability.
- Evidence suggests banks with low profitability, capital, and efficiency also tend to suffer from weak asset quality, creating a vicious cycle.
Key impediments to resolving nonperforming loans
- Weak economic recovery is a major factor but not the only impediment.
- Lack of distressed debt markets to move problem loans off bank balance sheets.
- Deficient legal frameworks and weak enforcement of debt contracts:
- Resolving insolvency cases takes 2.7 years on average.
- Courts specializing in insolvency cases do not exist in many jurisdictions.
- Difficulties in valuing collateral and supervisory gaps reduce incentives to recognize losses and write off loans.
- Absence of credit and asset registries undermines the ability to assess debtors’ liabilities and wealth, price risk, and value collateral, creating pricing gaps between buyers and sellers of distressed debt.
- Social and cultural factors (for example, reluctance to buy a neighbor’s foreclosed property) further discourage resolution.
Recommended policy responses and reforms
- Pursue sound economic policies to support growth and employment so borrowers can repay loans.
- Strengthen effective supervision to prevent buildup of problem loans and require banks to hold adequate provisions to facilitate recognition of losses.
- Use supervisory frameworks to provide incentives for banks to write off unrecoverable loans, including through higher capital charges and time limits to carry problem loans on balance sheets.
- Remove information gaps that hinder valuing risk and collateral and create pricing gaps:
- Develop well-functioning public credit and asset registries to improve credit-underwriting and facilitate debt workouts.
- Example: In Jamaica, the increased use of credit bureaus since 2014 has incentivized borrowers to preserve good credit ratings, helped loan recoveries, and reduced new nonperforming loans.
- Reform insolvency and debt-collection regimes:
- Improve judicial systems, establish specialized courts experienced in resolution, and expand use of fast-track and out-of-court debt-restructuring mechanisms to reduce resolution time and facilitate disposal of problem loans.
- Develop a domestic market for distressed assets:
- Establishing a pan-Caribbean nonperforming loan market can create economies of scale and help address cultural and social obstacles to resolution.
- Introduce asset management companies to jump-start the market, building on limited regional experience (as in The Bahamas).
Sequencing, prioritization, and regional coordination
- Design, prioritization, and sequencing of reforms should reflect country circumstances.
- Small Caribbean states would benefit from coordinating reforms to address regional institutional constraints.
- Ongoing initiatives cited as integrated efforts include creating a regional asset management company and credit bureaus, enhancing insolvency and debt-enforcement regimes, and establishing guidelines for collateral valuation in the Eastern Caribbean.
Source: Kimberly Beaton and Inci Otker, October 31, 2017 (IMF blog post).
References
- https://www.imf.org/wp-content/uploads/2017/10/BLOG-Caribbean-NPL-1024x600-Blue-ballpoint-pen-and-loan-agreement-William-Potter-iStockbyGettyimages-589581678.jpg
- IMF book
- https://www.imf.org/wp-content/uploads/2017/10/ENG_Oct_26_NPL3-4.jpg
- https://www.imf.org/wp-content/uploads/2017/10/Copy_ENG_Oct_26_NPL2-1.jpg