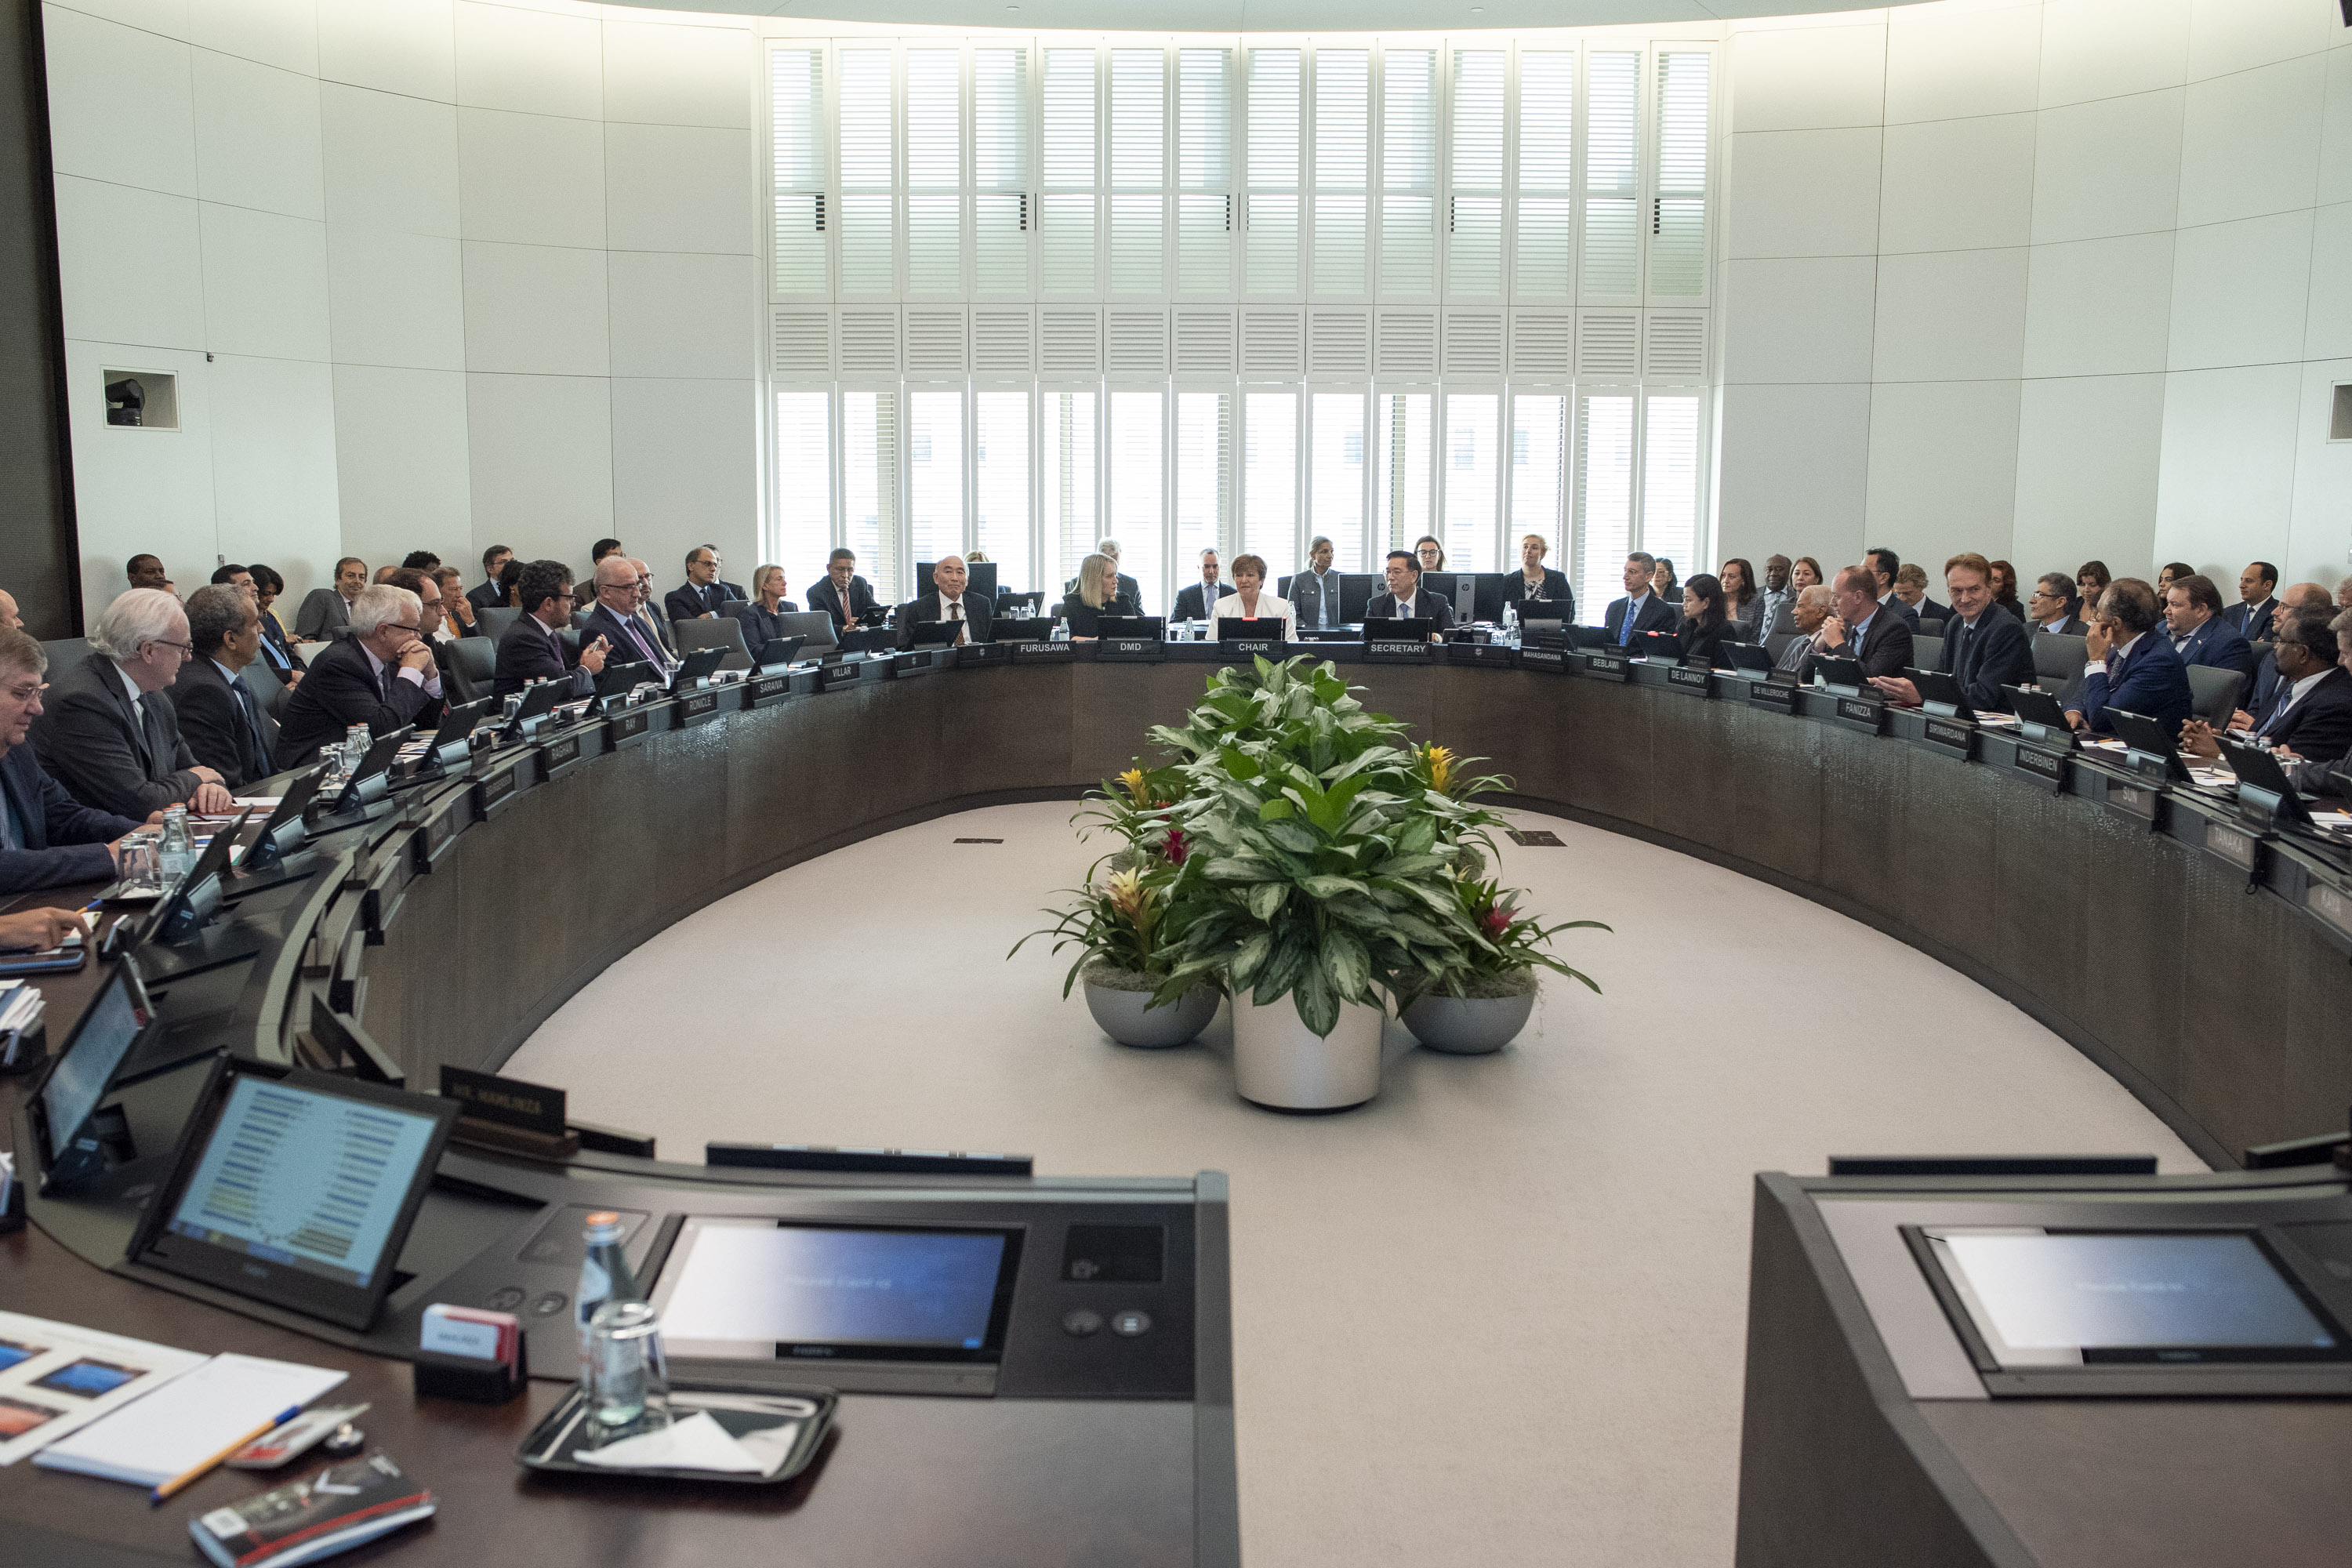
IMF Executive Board Concludes 2019 Article IV Consultation Discussions with People's Republic of China—Hong Kong Special Administrative Region
IMF News, December 30, 2019
Source details
- Canonical URL
- IMF Executive Board Concludes 2019 Article IV Consultation Discussions with People's Republic of China—Hong Kong Special Administrative Region
Other formats
Bibliographic details
- Published: December 30, 2019
Economic activity and outlook
- Economic activity in Hong Kong SAR weakened significantly in 2019 due to rising trade tensions between the U.S. and China and heightened uncertainty that took a toll on exports and investment; private consumption and visitor arrivals declined due to social unrest that started over the summer.
- GDP is expected to contract by 1.9 percent in 2019.
- Growth is projected to rise to 0.2 percent in 2020, led by private consumption.
- The pace of recovery over the medium term is expected to be slower than in previous recoveries because increased trade barriers and disruptions to global supply chains would be a drag on trade-related activities.
Financial markets, credit, and housing
- Financial markets continue to function smoothly and the HK dollar has traded within the convertibility undertaking range since the last FX operations conducted by the Hong Kong Monetary Authority in March 2019.
- Interbank rates have remained stable, net capital outflows have been limited, and market expectations of the HKD/USD exchange rate have remained well anchored.
- Credit growth moderated to 6.3 percent in September 2019, from a peak of 21.4 percent in October 2017.
- Housing prices declined by about 4 percent between May and September 2019 after rising for the first five months of 2019.
- Noted policy stance: Linked Exchange Rate System remains an appropriate anchor of stability.
Risks to the outlook
- External risks:
- Further escalation of trade tensions between the U.S. and China.
- A significant slowdown of Mainland China.
- Additional barriers, including potential restrictions by the U.S. against China in technology and the financial sectors.
- Domestic risks:
- Deterioration of the sociopolitical situation.
- Delays in addressing structural challenges of insufficient housing supply and high income inequality.
- A significant slowdown could trigger an adverse feedback loop between house prices, the real economy and the financial sector.
- Overall assessment: Risks to outlook are tilted to the downside.
Executive Board assessment and recommendations
- Directors noted the significant deterioration in economic activity due to the global growth slowdown, U.S.-China trade tensions, and ongoing social unrest.
- Directors agreed that Hong Kong SAR’s robust policy frameworks and ample buffers will help weather the challenges and welcomed authorities’ readiness to use these buffers as necessary.
- Fiscal policy:
- Countercyclical fiscal support should continue to be essential amid the slowdown.
- Welcomed recently announced stimulus targeted at the most vulnerable households and small- and medium-sized enterprises.
- Recommended a comprehensive medium-term fiscal package to cope with the cyclical downturn and address longer-term structural challenges associated with housing market imbalances, population aging, and income inequality, while preserving fiscal sustainability.
- Encouraged the authorities to consider tax reform over the medium to long term to boost revenues and foster equity.
- Saw scope for improving budget planning and execution, and for developing a long-term healthcare spending strategy.
- Housing and macroprudential policy:
- Supported the authorities’ three-pronged approach to contain housing market risks and improve housing affordability, with priority on increasing land allocation for residential housing.
- Noted effectiveness of macroprudential measures; any adjustment should be based on evolving financial stability risks.
- Encouraged phasing out the new residential stamp duty and replacing it with alternative non-discriminatory macroprudential measures once systemic risks from nonresident inflows dissipate.
- Financial sector:
- Underscored importance of safeguarding financial stability amid rising global volatility.
- Commended progress in implementing the 2014 FSAP recommendations.
- Recommended continued efforts to monitor vulnerabilities in the corporate sector, further strengthen the regulatory and supervisory framework, and facilitate innovation while managing risks.
- Noted that further development of green finance and the Greater Bay Area would help maintain competitiveness.
- External sector and communication:
- Directors observed that Hong Kong SAR’s external position is broadly in line with medium-term fundamentals and desirable policies.
- Stressed that preserving a track record of public communication would be key to the credibility of the currency board arrangement.
Selected economic and financial indicators (2015–24, as presented)
- Real GDP (percent change): 2015: 2.4; 2016: 2.2; 2017: 3.8; 2018: 3.0; 2019: -1.9; 2020: 0.2; 2021: 4.7; 2022: 2.8; 2023: 2.6; 2024: 2.5
- Private consumption (percent change): 2015: 4.8; 2016: 2.0; 2017: 5.6; 2018: 5.5; 2019: -2.3; 2020: -0.7; 2021: 4.3; 2022: 2.3
- Government consumption (percent change): 2015: 3.4; 2016: 4.2; 2017: 5.2; 2018: 5.8; 2019: 4.1; 2020: 3.5; 2021: 3.2
- Gross fixed capital formation (percent change): 2015: -3.2; 2016: -0.1; 2017: 2.9; 2018: -10.2; 2019: -1.0; 2020: 7.6
- Inventories (contribution to growth): 2015: -1.2; 2016: 0.9; 2017: 0.5; 2018: -0.5; 2019: 0.0
- Net exports (contribution to growth): 2015: 0.8; 2016: -0.3; 2017: -1.4; 2018: 1.9; 2019: -0.2
- Output gap (in percent of potential): 2015: 0.3; 2016: -3.1; 2017: -4.6; 2018: -2.1; 2019: -1.6; 2020: -1.5
- Gross national saving (percent of GDP): 2015: 24.9; 2016: 25.5; 2017: 26.7; 2018: 26.0; 2019: 25.2; 2020: 25.1; 2021: 25.3; 2022: 25.6; 2023: 25.7
- Gross domestic investment (percent of GDP): 2015: 21.5; 2016: 22.0; 2017: 21.7; 2018: 19.7; 2019: 20.0; 2020: 20.6; 2021: 21.1; 2022: 21.4
- Saving-investment balance (percent of GDP): 2015: 3.3; 2016: 4.0; 2017: 4.4
- Employment (percent change): 2015: 1.4; 2016: 1.1; 2017: 0.7
- Unemployment rate (percent, period average): 2015: 3.1
- Real wages (percent change): 2015: 1.2; 2016: 1.3
- Consumer prices (percent change): 2015: 1.5; 2016: 1.8
- GDP deflator (percent change): 2015: 3.6; 2016: 1.6
- Consolidated budget balance (percent of GDP): 2015: 0.6; 2016: 4.5
- Revenue (percent of GDP): 2015: 18.8; 2016: 23.0; 2017: 23.3; 2018: 20.7; 2019: 20.8; 2020: 21.0
- Expenditure (percent of GDP): 2015: 18.2; 2016: 18.6; 2017: 17.7; 2018: 18.7; 2019: 20.4; 2020: 20.3; 2021: 20.2
- Fiscal reserves (as of March 31, percent of GDP): 2015: 35.1; 2016: 38.3; 2017: 41.4; 2018: 41.2; 2019: 41.1; 2020: 39.0; 2021: 37.9; 2022: 37.1; 2023: 36.1
- Loans for use in Hong Kong SAR (excl. trade financing, percent change): 2015: 6.3; 2016: 8.0; 2017: 16.1; 2018: 6.5; 2019: 8.5; 2020: 7.5; 2021: 7.4; 2022: 7.2
- House prices (end of period, percent change): 2015: 7.9; 2016: 14.7; 2017: 1.0; 2018: 9.9; 2019: 8.1; 2020: 7.8
- Credit-to-GDP gap 1/: 2015: 15.3; 2016: 11.5; 2017: 19.3; 2018: 9.8; 2019: 10.6; 2020: 9.4; 2021: 6.2
- Hang Seng stock index (percent change): 2015: -7.2; 2016: 36.0; 2017: -13.6
- Merchandise trade (percent change, export value): 2015: -1.8; 2016: -3.9
- Merchandise trade (percent change, import value): 2015: -4.1; 2016: 8.7; 2017: 8.4; 2018: -5.6; 2019: 3.9; 2020: 3.7
- Foreign exchange reserves (in billions of U.S. dollars, end-of-period): 2015: 358.8; 2016: 386.3; 2017: 431.4; 2018: 424.7; 2019: 425.3; 2020: 425.9; 2021: 427.0; 2022: 428.5; 2023: 429.9; 2024: 430.5
- Foreign exchange reserves (percent of GDP): 2015: 116.0; 2016: 120.4; 2017: 126.2; 2018: 117.1; 2019: 117.7; 2020: 116.4; 2021: 109.2; 2022: 104.5; 2023: 100.2; 2024: 96.0
- Net international investment position (percent of GDP): 2015: 324.2; 2016: 359.2; 2017: 417.0; 2018: 356.7; 2019: 363.8; 2020: 364.4; 2021: 345.3; 2022: 333.7; 2023: 323.1; 2024: 313.1
- Market rate (HK$/US$, period average): 2015: 7.752; 2016: 7.762; 2017: 7.793; 2018: 7.838
IMF Press Release No. 19/485 — December 30, 2019
References
- https://www.imf.org/-/media/images/imf/bios/imfboard.jpg
- The Executive Board
- People's Republic of China - Hong Kong Special Administrative Region and the IMF
- People's Republic of China and the IMF
- IMF Policy Advice -- A Factsheet
- Press Releases
- PRESS CENTER
- http://www.imf.org/external/np/sec/misc/qualifiers.htm
- https://www.imf.org/en/home