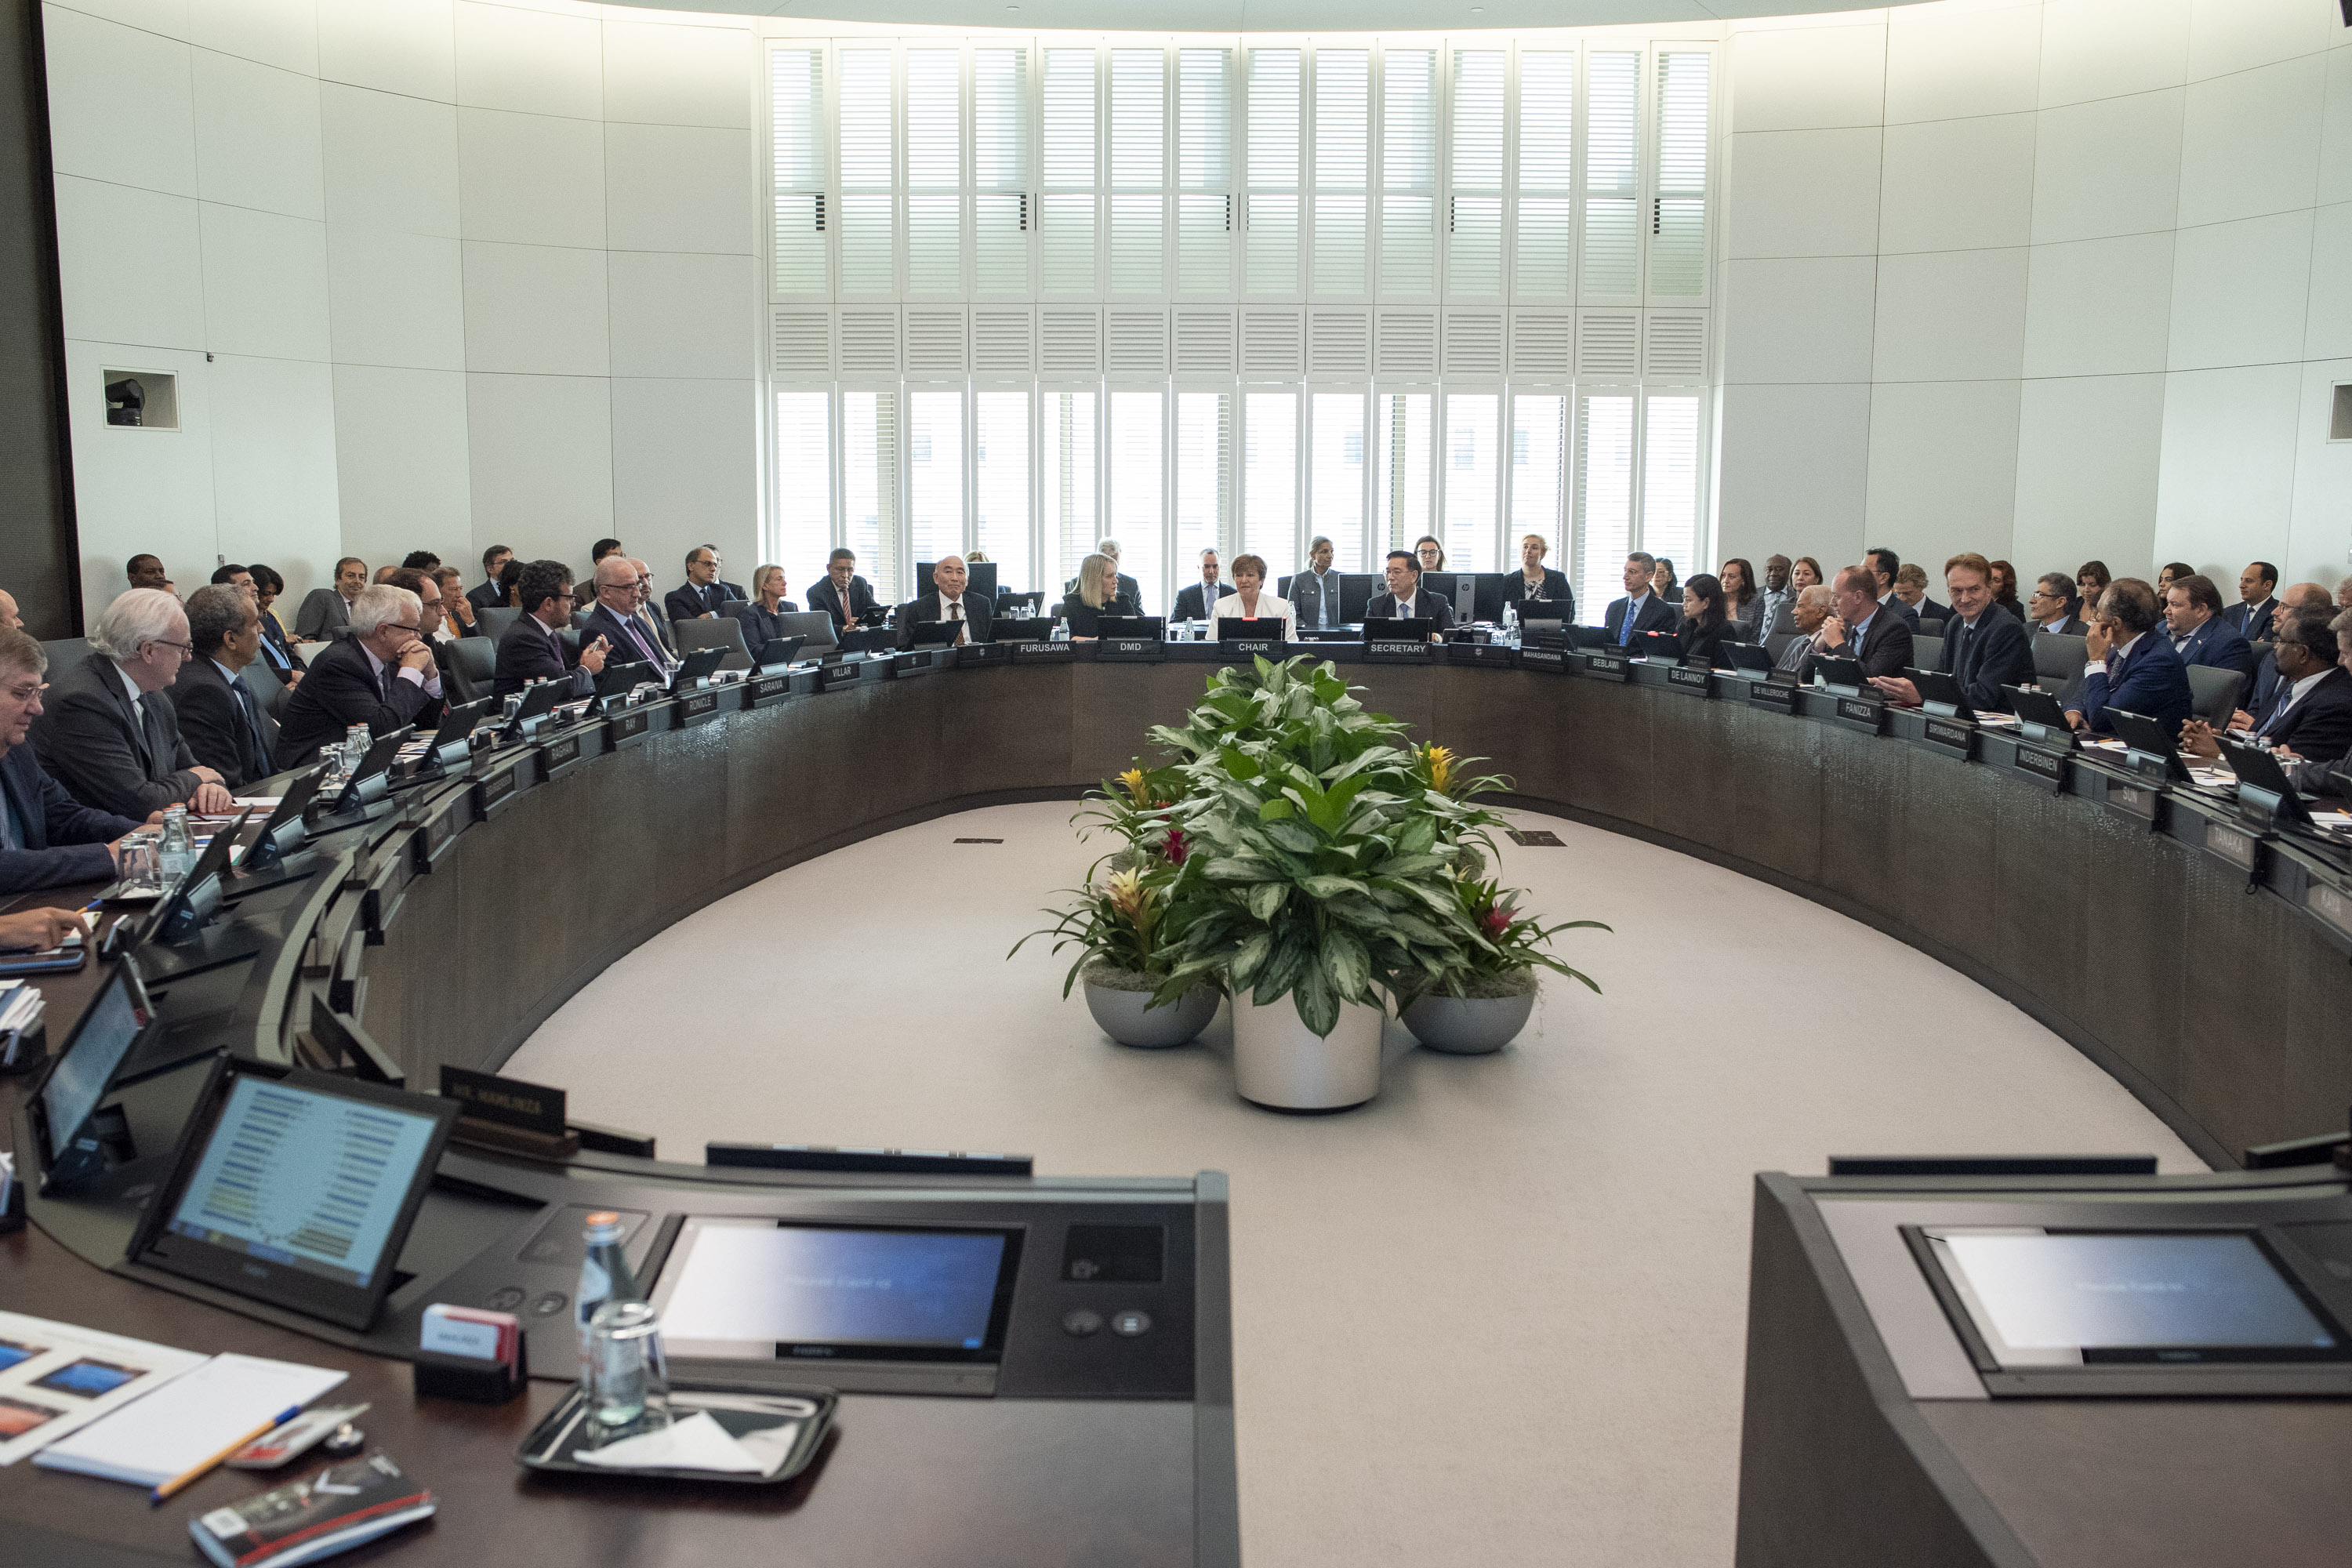
IMF Executive Board Concludes the 2026 Article IV Consultation with The Gambia and Completes the Fifth Review Under the Extended Credit Facility and the Second Review Under the Resilience and Sustainability Facility Arrangements
IMF News, July 6, 2026
Source details
- Canonical URL
- IMF Executive Board Concludes the 2026 Article IV Consultation with The Gambia and Completes the Fifth Review Under the Extended Credit Facility and the Second Review Under the Resilience and Sustainability Facility Arrangements
Other formats
Bibliographic details
- Published: July 6, 2026
Program actions, disbursements, and access changes
- Executive Board concluded the 2026 Article IV Consultation and completed the Fifth Review under the Extended Credit Facility (ECF) and the Second Review under the Resilience and Sustainability Facility (RSF).
- Enabled an immediate overall disbursement of SDR16.58 million (about US$22.51 million under both the ECF and the RSF.
- ECF review completion: immediate disbursement of SDR6.22 million (about US$8.44 million), bringing total disbursements under the ECF to SDR55.97 million (about US$75.98 million).
- RSF second review: immediate disbursement of SDR10.36 million (about US$14.06 million), bringing total access under the RSF to about SDR 25.90 million (about US$ 35.16 million).
- Executive Board approved:
- a six-month extension of the ECF and RSF arrangements;
- an augmentation of access under the ECF arrangement of SDR 12.44 million (20 percent of quota);
- rephasing of access under both ECF and RSF to address balance of payments and implementation timelines.
- Rationale: ECF augmentation to help address emerging balance of payments needs due to the war in the Middle East; RSF extension and rephasing to allow additional time to implement complex climate-related reforms.
Macroeconomic outlook and risks
- Recent performance:
- Economic activity remains robust, with GDP growth estimated at 6 percent in 2025.
- Headline inflation rebounded in April following a period of decline; inflation has picked up in recent months.
- Near-term projections:
- Growth is projected to slow to 4.7 percent in 2026 before stabilizing at 5 percent over the medium term.
- Risks:
- Impact of the war in the Middle East is weighing on the macroeconomic outlook and heightening domestic risks.
- Elevated downside risks from spillovers from the war in the Middle East as well as climate shocks.
- Inflationary pressures have reemerged, delaying convergence to the central bank’s target; downside risks remain significant.
Fiscal, monetary, and financial sector policy directions
- Fiscal policy:
- In response to end-2025 fiscal slippages, fiscal policy will be tightened in 2026 through additional revenue mobilization and reprioritization of spending.
- Authorities committed to tightening fiscal policy in 2026 and 2027 to correct the fiscal slippage in 2025.
- Importance of strict expenditure prioritization and control in the 2026 election year; accommodation of targeted short-term mitigation measures, including cash transfers financed by a World Bank grant.
- Approved waivers for nonobservance of the end‑December 2025 quantitative performance criteria on net domestic borrowing and the domestic primary balance based on corrective measures taken by the authorities.
- Monetary and exchange rate policy:
- Central bank to maintain a data‑driven, appropriately tight stance to contain inflation and safeguard external stability.
- Maintaining a market-determined exchange rate is critical to preserving external stability.
- Positive development: implementation of measures to refrain from quasi-fiscal operations.
- Need to strengthen supervisory capacity, advance risk-based supervision, and closely monitor sovereign exposures to maintain financial stability.
- Structural and governance policies:
- Accelerate structural reforms to strengthen fiscal institutions, SOE management and governance, anti‑corruption framework, and the business environment to support private sector‑led growth and job creation.
- Emphasized actions: operationalize the anti‑corruption commission; expedite Cabinet approval and enactment of the revised AML/CFT law and the National Audit Office Act; accelerate implementation of governance diagnostic recommendations.
- Importance of integrating climate risks into the macro‑fiscal framework.
Capacity development and program implementation
- IMF capacity development (CD) role:
- The Gambia ranks sixth in total CD allocation over FY2022–26 (US$10.4 million) and highest on a per capita basis among the top 15 recipients of CD.
- CD has supported progress in domestic revenue mobilization, exchange rate stabilization, macro‑financial stability, public financial management, SOE oversight, economic data reporting, and climate‑related reforms under the RSF.
- Continued CD will be critical to strengthen implementation capacity in revenue administration, public financial management, financial sector oversight, and statistics, and to address remaining data gaps.
- Program performance:
- Implementation of the ECF program and RSF reforms has been mixed; stronger reform implementation is needed to safeguard macro‑financial stability and support resilient, inclusive growth.
Executive Board and staff assessments
- Deputy Managing Director Bo Li highlights:
- Strong growth alongside rebounding headline inflation driven by higher food and energy costs.
- Authorities’ commitment to fiscal tightening, safeguarding fuel revenue, containing spending pressures in the election year, and reinforcing public financial management and SOE oversight.
- Need for tight monetary policy, exchange rate flexibility, strengthened supervision, and continued progress on structural reforms.
- Steadfast implementation of the climate agenda under the RSF to support resilience, stability, and mobilize additional financing.
- Executive Directors agreed with the thrust of the staff appraisal:
- Welcomed strong economic growth and noted recent inflation rebound.
- Noted mixed program performance and emphasized need to strengthen reform implementation given downside risks.
- Welcomed authorities’ commitment to fiscal consolidation in 2026–27 and underscored stronger domestic revenue mobilization, expenditure controls, and improvements in public financial, investment, and debt management.
- Supported a tight, data‑dependent monetary policy, exchange rate flexibility, and strengthened regulatory/supervisory framework.
- Called for accelerated structural reforms, strengthened governance, operationalization of anti‑corruption and audit frameworks, and improved business environment.
- Affirmed the importance of Fund capacity development to support program implementation.
Key selected economic indicators (2023–2027)
- GDP at constant prices (percent change): 2023: 5.9; 2024: 5.6; 2025: 6.0; 2026: 4.7; 2027: 5.1
- GDP deflator: 2023: 13.7; 2024: 5.8; 2025: 8.4; 2026: 6.8
- Consumer prices (average): 2023: 17.0; 2024: 11.6; 2025: 7.9; 2026: 7.5; 2027: 6.2
- Consumer prices (end of period): 2023: 17.3; 2024: 10.2; 2025: 6.6; 2026: 7.0; 2027: 5.5
- Exports, f.o.b (US$ values): 2023: 535.5; 2024: 10.7; 2025: 12.2; 2026: -2.7; 2027: 4.8
- Imports, f.o.b (US$ values): 2023: 74.7; 2024: 14.5; 2025: -1.3; 2026: 10.4; 2027: 2.7
- Broad money (contributions to broad money growth; percent): 2023: 8.8; 2024: 24.1; 2025: 3.0
- Net foreign assets (contrib.): 2023: 4.4; 2024: 0.1; 2025: 3.7
- Net domestic assets (contrib.): 2023: 0.4; 2024: 9.6; 2025: -0.7
- Credit to central government (net): 2023: -2.5; 2024: 6.7; 2025: 5.4; 2026: 2.9; 2027: 2.8
- Credit to the private sector (net): 2023: 2.1; 2024: 4.3; 2025: 4.1
- Domestic revenue (taxes and other revenues, percent of GDP): 2023: 14.0; 2024: 15.4; 2025: 15.1; 2026: 15.5
- Tax Revenue (percent of GDP): 2023: 10.9; 2024: 12.8; 2025: 12.6; 2026: 13.4
- Grants (percent of GDP): 2023: 8.2; 2024: 7.3; 2025: 9.0; 2026: 9.4
- Total expenditures (percent of GDP): 2023: 23.9; 2024: 25.3; 2025: 29.4; 2026: 26.7; 2027: 25.9
- Interest (percent of gov. revenue): 2023: 22.1; 2024: 21.3; 2025: 22.0; 2026: 13.5
- Net lending (+)/borrowing (–) (percent of GDP): 2023: -3.6; 2024: -4.0; 2025: -5.0; 2026: 0.0; 2027: -1.0
- Net incurrence of liabilities (percent of GDP): 2023: 4.5; 2024: 1.0
- Public debt (percent of GDP): 2023: 77.4; 2024: 78.8; 2025: 82.1; 2026: 73.5; 2027: 67.8
- External public debt (percent of GDP): 2023: 49.4; 2024: 50.1; 2025: 51.2; 2026: 48.0; 2027: 42.3
- External public debt (millions of US$): 2023: 1120.1; 2024: 1168.4; 2025: 1318.5; 2026: 1306.6; 2027: 1264.6
- External current account balance excluding official transfers (percent of GDP): 2023: -8.2; 2024: -9.1; 2025: -6.4; 2026: -8.4; 2027: -5.7
- External current account balance including official transfers (percent of GDP): 2023: -5.4; 2024: -7.0; 2025: -4.1; 2026: -5.6; 2027: -4.4
- Gross official reserves (millions of US$): 2023: 474.3; 2024: 533.5; 2025: 586.2; 2026: 592.1
- Gross official reserves (months of next year's imports): 2023: 4.2
- Gross investment (percent of GDP): 2023: 24.7; 2024: 25.1; 2025: 25.2; 2026: 26.1
- Gross savings (percent of GDP): 2023: 19.2; 2024: 17.5; 2025: 21.0; 2026: 19.6; 2027: 21.7
- Nominal GDP (billions of dalasi): 2023: 145.9; 2024: 162.9; 2025: 187.2; 2026: 207.8; 2027: 233.1
- GDP per capita (US$): 2023: 857.5; 2024: 861.9; 2025: 912.9; 2026: 955.6; 2027: 1002.3
- Use of Fund resources (millions of SDRs) — Disbursements: 2023: 24.9; 2024: 21.8; Of which: ECF Augmentation: 12.4
- Repayments (millions of SDRs): 2023: -3.9; 2024: -5.2; 2025: -9.8; 2026: -14.3
- PV of overall debt-to-GDP ratio (percent): 2023: 65.1; 2024: 69.1; 2025: 71.0; 2026: 62.9; 2027: 58.3
IMF Press Release No. 26/239, July 6, 2026
References
- https://www.imf.org/-/media/images/imf/bios/imfboard.jpg
- The Executive Board
- The Gambia and the IMF
- IMF Policy Advice -- A Factsheet
- IMF-World Bank Debt Sustainability Framework for Low-Income Countries -- A Factsheet
- Press Releases
- PRESS CENTER
- approved on January 12, 2024
- approved on June 18, 2025
- The Gambia’s country page
- http://www.IMF.org/external/np/sec/misc/qualifiers.htm
- https://www.imf.org/en/home