Portfolio Investment in Emerging Markets: More Than Just Ebb and Flow
IMF Blog, November 7, 2014
Source details
- Canonical URL
- Portfolio Investment in Emerging Markets: More Than Just Ebb and Flow
Other formats
Bibliographic details
- Authors: Evan Papageorgiou
- Published: November 7, 2014
Main findings on portfolio flows and concentration
- Total portfolio flows into emerging market bonds and equities have continued largely uninterrupted despite retail outflows following 2013’s “taper tantrum.”
- Allocation of emerging market assets in the portfolios of developed market investors increased by 2.5 times over the last decade—from 5% in 2002 to 13% in 2012.
- The systemic risk arises from concentration:
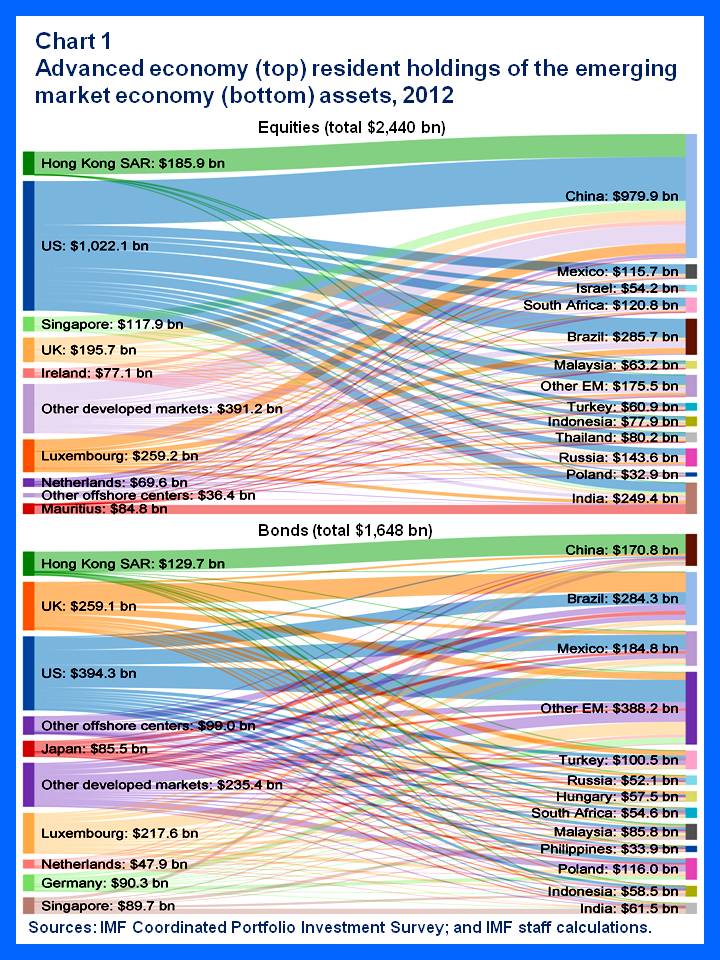
- $4.1 trillion of allocations are concentrated in a few source economies and a few recipient emerging market economies.
- 12 out of 190 emerging market economies receive 80% of all portfolio flows from advanced economies.
- Portfolio equity allocations from U.S. residents alone account for more than a third of the total for each major emerging market economy.
Volatility, liquidity, and transmission of shocks
- Low interest rates in advanced economies have driven investors to seek higher returns in emerging markets, increasing allocations and interconnectedness.
- Declines in market liquidity—arising from changes in the structure of financial markets—and increases in volatility are central financial-stability concerns for emerging market economies, even in the absence of large portfolio outflows.
- The Global Financial Stability Report estimates the largest increases in volatility between the low (normal) and the high (risk averse) states are for emerging market assets such as bonds, currencies, and equities, in addition to high-yield bonds (see Chart 2 for bonds).
- Across major emerging market economies, the estimated sensitivity of emerging market local currency government bonds is generally higher for a volatility shock than for a commensurate U.S. interest rate shock (Chart 3), suggesting volatility may be a bigger policymaker concern than interest rate movements.
Policy implications and recommendations
- Policymakers need to recognize latent risks from the synchronized relationship between advanced and emerging market financial systems.
- Implement policies to ensure smooth market functioning and financial stability, with particular attention to:
- Monitoring and managing the concentration of portfolio allocations across source and recipient economies.
- Strengthening measures to preserve market liquidity under stress.
- Preparing for volatility-driven pressures on local currency government bonds, currencies, and equity markets.
Source: Portfolio Investment in Emerging Markets: More Than Just Ebb and Flow (IMF blog, November 7, 2014).
References
- https://www.imf.org/wp-content/uploads/2014/09/evan-papageorgio.jpg
- Evan Papageorgiou
- Global Financial Stability Report
- arising from changes in the structure of financial markets
- emerging market assets
- https://www.imf.org/wp-content/uploads/2014/11/gfsr-chap1-devems-chart-1-rev.jpg
- https://www.imf.org/wp-content/uploads/2014/11/gfsr-chap1-devems-chart-2.jpg
- https://www.imf.org/wp-content/uploads/2014/11/gfsr-chap1-devems-chart-3.jpg