Global Banks May Grow More Vulnerable to a Dollar Disruption
IMF Blog, October 11, 2019
Source details
- Canonical URL
- Global Banks May Grow More Vulnerable to a Dollar Disruption
Other formats
Bibliographic details
- Authors: Claudio Raddatz, Adolfo Barajas
- Published: October 11, 2019
Role of the US dollar in non-US banking
- Non-US banks play a key role in dollar lending worldwide, financing transactions such as a Mexican airline buying Brazilian airplanes with US dollar loans obtained from non-US banks.
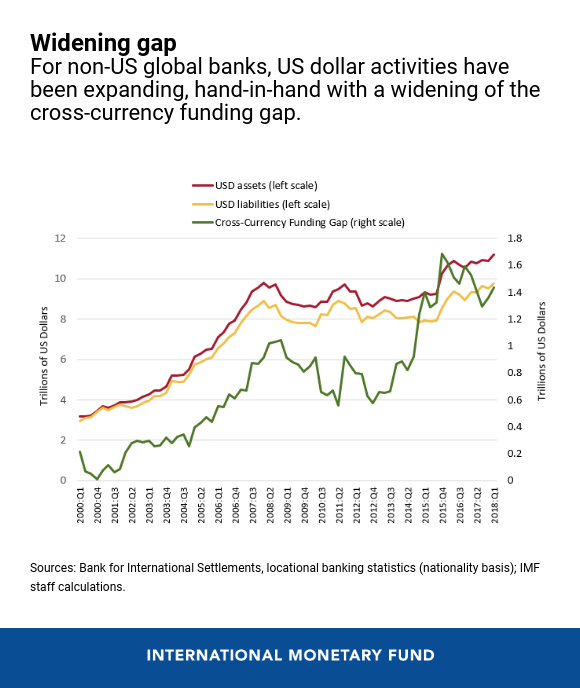
- Non-US banks’ dollar assets rose to $12.4 trillion by mid-2018 from $9.7 trillion in 2012.
- Non-US banks’ dollar assets remain comparable to pre-crisis levels relative to their total assets.
Sources of dollar funding and structural vulnerabilities
- Unlike US banks, non-US banks have limited access to a stable base of dollar deposits and therefore rely heavily on short-term and potentially more volatile funding sources, such as commercial paper and loans from other banks.
- When short-term funding is insufficient, non-US banks turn to foreign currency swaps, which are more expensive and can be unreliable in times of stress.
- An increase in dollar funding costs can reverberate across the global financial system and boost the odds of bank defaults in home economies of non-US banks.
Indicators developed to measure exposure and vulnerability
- Cross-currency funding gap:
- Has widened to about $1.4 trillion, or 13 percent of assets, from $1 trillion, or 10 percent of assets, in mid-2008.
- Reflects the amount of financing that must be filled by instruments like foreign currency swaps, increasing vulnerability.
- Highly liquid dollar assets measure:
- Shows that dollar liquidity has improved since the crisis but remains lower than the overall liquidity of banks’ balance sheets.
- US dollar stable funding ratio:
- Reflects banks’ ability to fund dollar assets over a long time horizon using stable sources.
- Has improved only moderately since 2008.
Transmission channels and differential impacts
- Higher dollar funding costs:
- Increase the odds of bank defaults in home economies of non-US banks that rely on dollar funding.
- Increase stress in third countries that receive loans from non-US banks.
- Emerging-market borrowers are most vulnerable because they cannot easily find alternative sources of funding.
- US dollar funding fragility can act as an amplifier: negative effects are especially pronounced when any of the chapter’s measures indicates heightened vulnerability.
Policy mitigators and recommendations
- Strengthen overall health of the banking system:
- More profitable, better capitalized banks provide a cushion against dollar disruptions.
- Build larger reserve holdings:
- Central bank reserves can be used to fill dollar liquidity gaps if they dry up.
- Maintain or arrange central bank swap lines:
- Central bank swap arrangements that provide access to US dollars during periods of stress can play an important role, as they did during the 2007-2008 crisis.
- Improve measurement and monitoring:
- Use the developed set of indicators to properly measure non-US banks’ exposure to dollar funding and their vulnerability.
Source: IMF blog post "Global Banks May Grow More Vulnerable to a Dollar Disruption" (October 11, 2019).