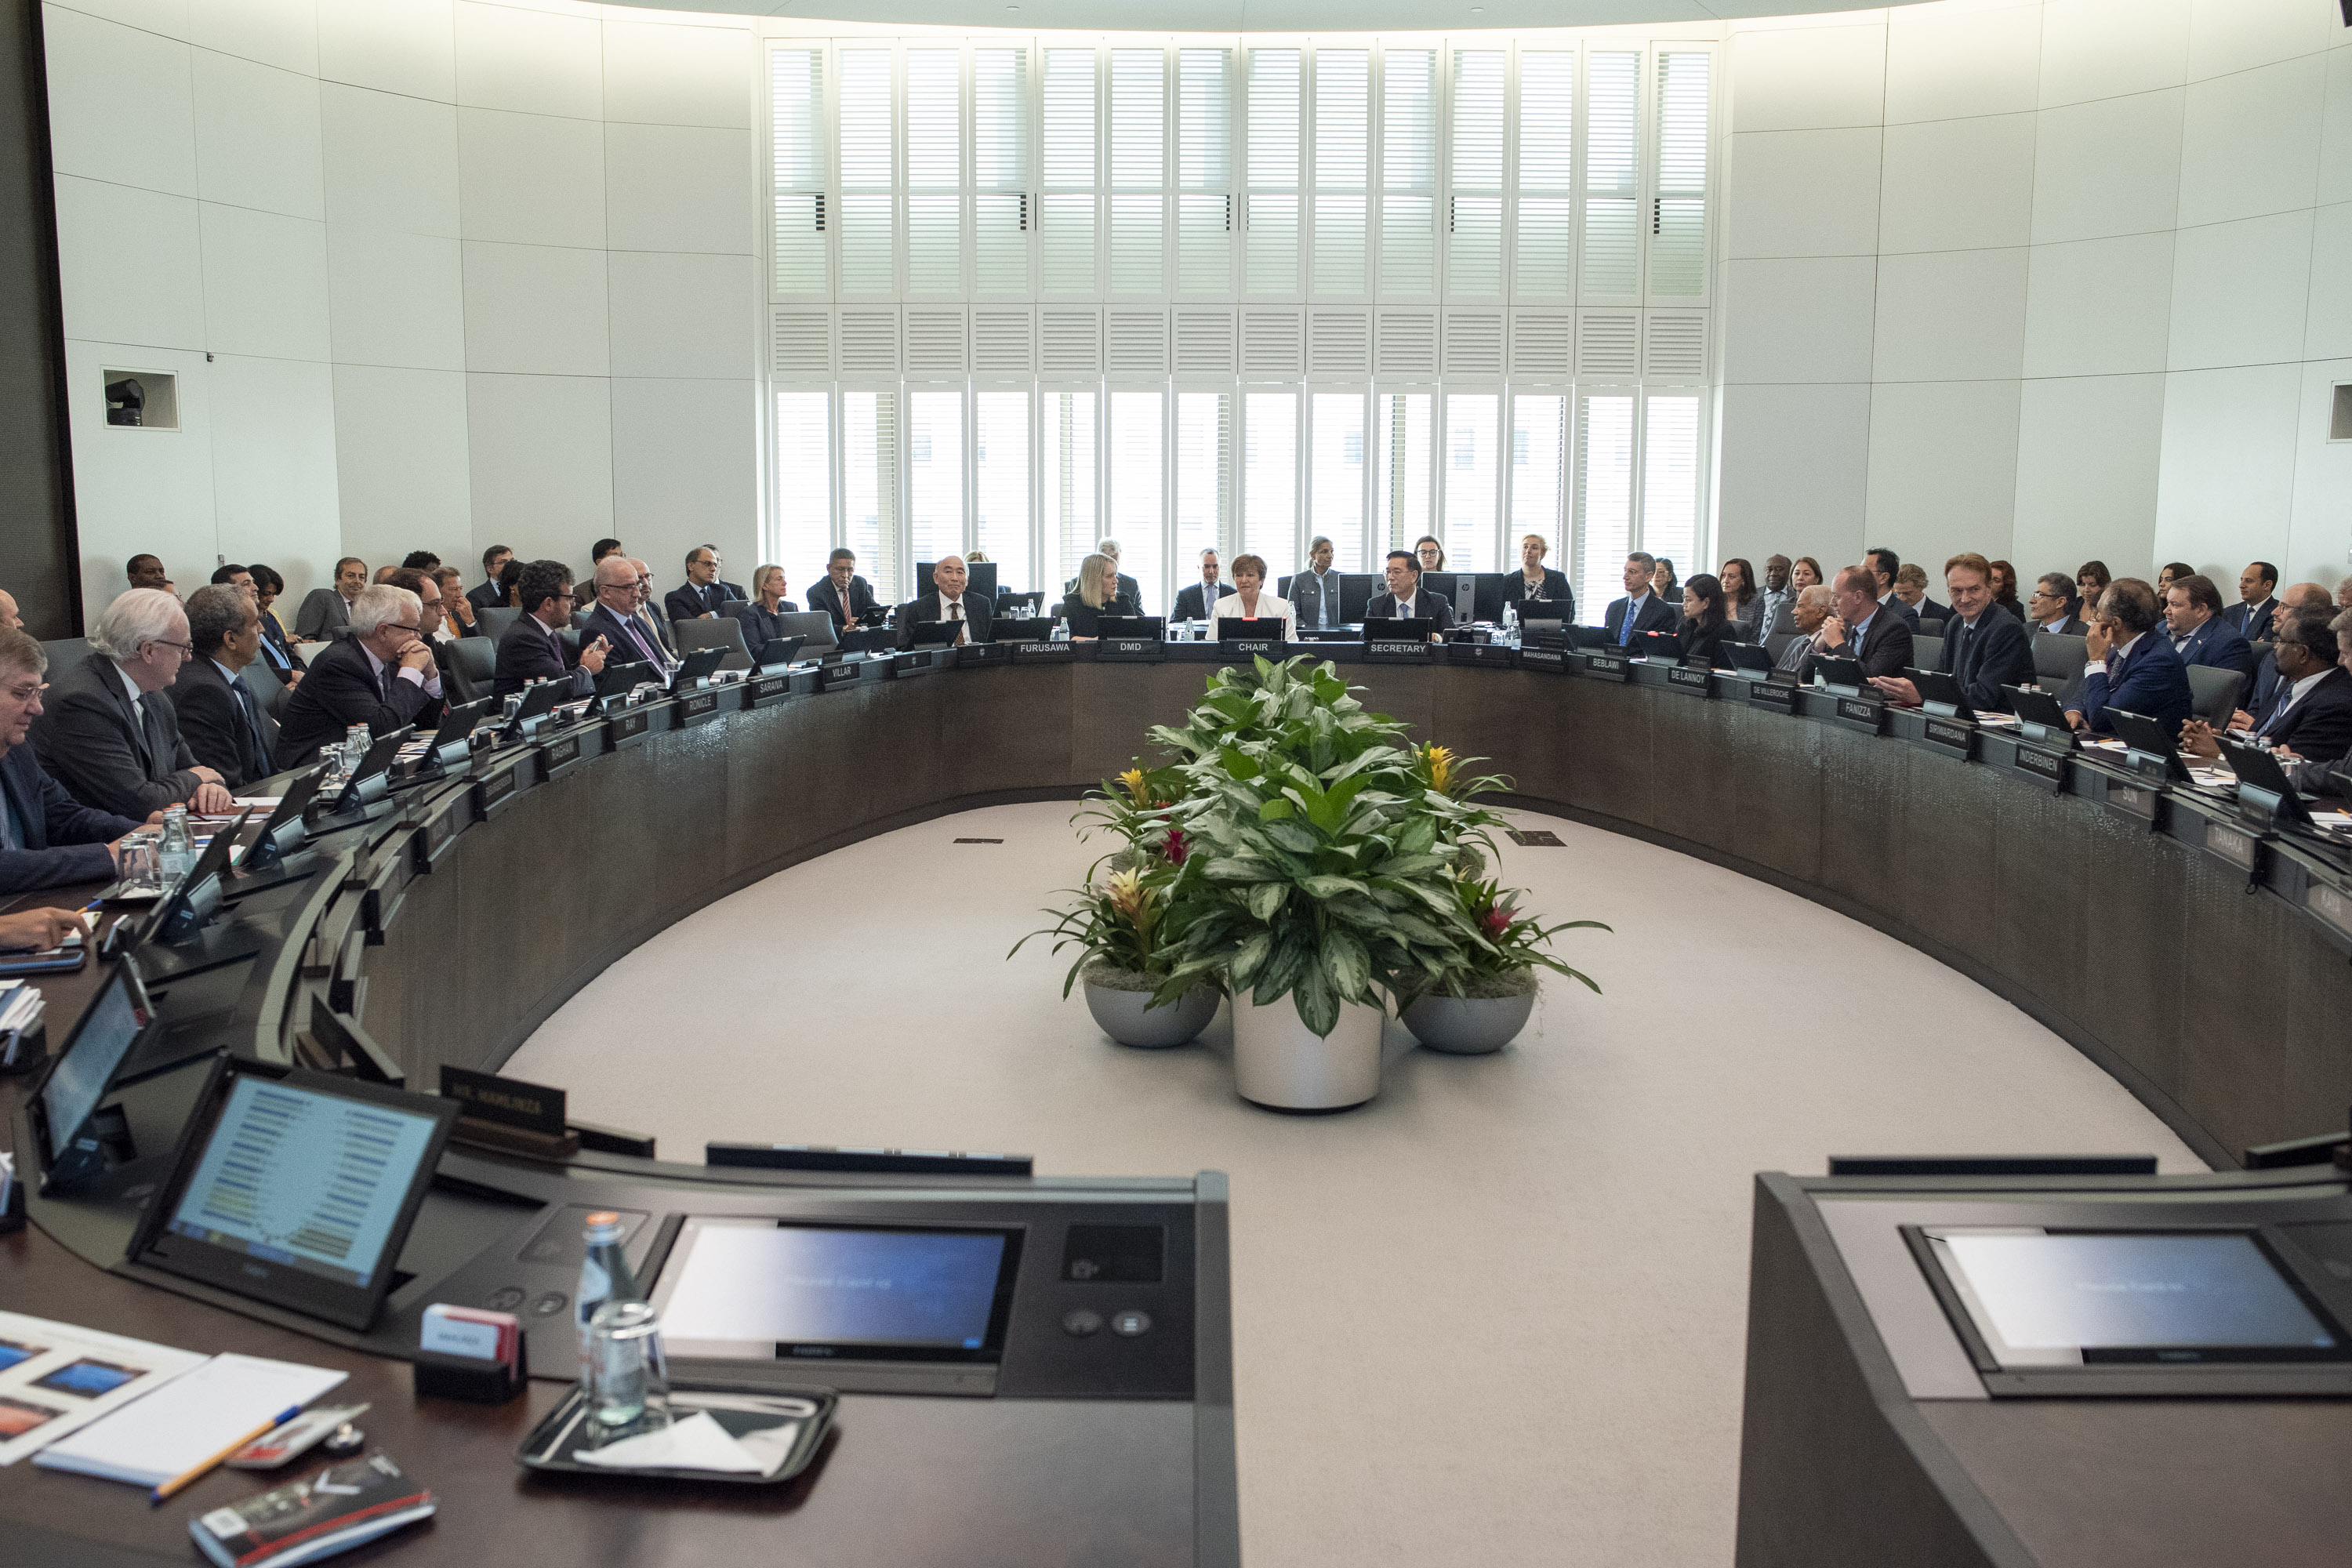
IMF Executive Board 2020 Article IV Consultation with the Republic of Poland
IMF News, February 8, 2021
Source details
- Canonical URL
- IMF Executive Board 2020 Article IV Consultation with the Republic of Poland
Other formats
Bibliographic details
- Published: February 8, 2021
Economic impact and outlook
- 2020 recession estimated at -3.4 percent, described as "among the least severe in the European Union."
- Growth projections:
- 2021: 2.7 percent (limited by ongoing restrictions early in 2021; rebound expected later as vaccine access improves)
- 2022: 5.1 percent (further acceleration expected)
- Medium term: sizeable new grants from the EU expected to facilitate strong investment and boost growth.
- Output gap (percent of potential GDP):
- 2019: 0.9
- 2020: -2.7
- 2021: -2.5
- 2022: -0.8
- 2023: 0.0
- Inflation:
- Average CPI inflation: 2019: 2.3; 2020: 3.4; 2021: 2.2; 2022: 2.5
- End of period CPI inflation (reported): 2.1
- Projection: Inflation projected to fall further in 2021 while remaining near the target over the medium term.
- Unemployment rate (average, according to LFS):
- 2019: 3.3
- 2020: 4.9
- 2021: 4.6
Fiscal stance and public finances
- Poland entered the pandemic with substantial fiscal buffers, enabling a strong fiscal response.
- Pandemic-related fiscal measures focused on preserving jobs and incomes:
- Wage subsidies
- Benefits for self-employed and unemployed workers
- Partially forgivable loans for companies
- Implementation described as "frontloaded and robust"
- Fiscal outcomes:
- General government net lending/borrowing:
- 2019: -0.7 percent of GDP
- 2020: -8.4 percent of GDP
- 2021 (projection): -5.1 percent of GDP
- 2022 (projection): -3.2 percent of GDP
- General government primary balance:
- 2019: 0.6 percent of GDP
- 2020: -7.1 percent of GDP
- 2021 (projection): -4.1 percent of GDP
- 2022 (projection): -1.6 percent of GDP
- 2023 (projection): -2.2 percent of GDP
- General government debt:
- 2019: 45.7 percent of GDP
- 2020: 58.6 percent of GDP
- 2021 (projection): 59.1 percent of GDP
- 2022 (projection): 57.4 percent of GDP
- 2023 (projection): 56.8 percent of GDP
- 2024 (projection): 57.0 percent of GDP
- 2025 (projection): 57.5 percent of GDP
- Medium-term projection: fiscal deficit projected to stabilize around 3¼ percent of GDP, with debt stable around 58 percent of GDP.
- Note: One-off revenues from the Pillar II pension conversion are assumed for 2022.
Monetary policy and financial sector
- Monetary easing measures:
- Policy interest rate reduced to near zero.
- Central bank implemented an asset purchase program.
- Inflation drivers in early 2020: tight labor markets and regulated price increases.
- Banking sector:
- Macro-prudential measures implemented to mitigate crisis impact.
- Bank earnings have declined; asset quality has deteriorated only modestly; banks remain well capitalized.
- Legal risks from foreign-currency denominated mortgages remain a source of uncertainty and potential losses for banks.
- Supervisory and regulatory developments:
- Supervisory actions welcomed to mitigate crisis impact.
- Enhanced autonomy of the Financial Supervisory Authority and increased focus on AML/CFT compliance noted.
- Directors recommended proactively addressing implications of court rulings on foreign exchange mortgage lawsuits.
- Directors considered that redesigning the bank asset tax could support private credit during the recovery.
- Directors called for continued vigilance, particularly on cooperative banks, given higher credit risk and lower earnings.
Executive Board assessment and policy recommendations
- Overall assessment:
- Directors welcomed effective policy support during the pandemic-induced recession and judged Poland well positioned for a durable recovery given strong fundamentals, available policy space, and sizeable new grants expected from the EU.
- High uncertainty calls for continued vigilance and flexibility in the near term.
- Fiscal policy recommendations:
- Extend more targeted fiscal support in response to the second wave while ensuring adequate coverage for indirectly affected sectors.
- Once recovery is firmly underway, gradually reduce the fiscal deficit over the medium term to replenish fiscal buffers, including through improved revenue administration and expenditure efficiency.
- Monetary policy recommendations:
- With inflation projected to remain near the target, maintain accommodative monetary policy stance until recovery is well established.
- Continue clear policy communication to support the effectiveness of the asset purchase program and limit the need for foreign exchange interventions.
- Structural and investment priorities:
- Advance structural reforms to minimize scarring from the crisis.
- Prioritize labor market reforms that encourage participation and foster labor reallocation in the post-pandemic economy.
- Boost public investment, including through digitalization and green investments, supported by the Next Generation EU funds.
- Enhance absorptive capacity and coordination among government entities for effective use of EU funds.
Balance of payments and external sector
- Current account balance, percent of GDP:
- 2019: 0.5
- 2020: 1.9
- 2021 (projection): 0.4
- 2022 (projection): 0.2
- 2023 (projection): -0.1
- Total external debt, percent of GDP:
- 2019: 59.4
- 2020: 59.9
- 2021 (projection): 58.5
- 2022 (projection): 51.2
- 2023 (projection): 45.5
- 2024 (projection): 42.4
- 2025 (projection): 39.4
Key nominal figures (memorandum)
- Nominal GDP (billion zloty):
- 2019: 2287.7
- 2020: 2285.2
- 2021 (projection): 2418.7
- 2022 (projection): 2599.3
- 2023 (projection): 2775.8
- 2024 (projection): 2926.8
- 2025 (projection): 3076.4
IMF Executive Board 2020 Article IV Consultation with the Republic of Poland — Press Release No. 21/34 (February 8, 2021).
References
- https://www.imf.org/-/media/images/imf/bios/imfboard.jpg
- The Executive Board
- IMF COVID-19 Hub
- Policy Tracker
- Financial Assistance
- Questions & Answers
- Republic of Poland and the IMF
- IMF Policy Advice -- A Factsheet
- Press Releases
- PRESS CENTER
- http://www.IMF.org/external/np/sec/misc/qualifiers.htm
- https://www.imf.org/en/home