IMF Executive Board Approves US$12 billion Extended Arrangement Under the Extended Fund Facility for Egypt
IMF News, November 11, 2016
Source details
- Canonical URL
- IMF Executive Board Approves US$12 billion Extended Arrangement Under the Extended Fund Facility for Egypt
Other formats
Bibliographic details
- Published: November 11, 2016
Approval and Financing
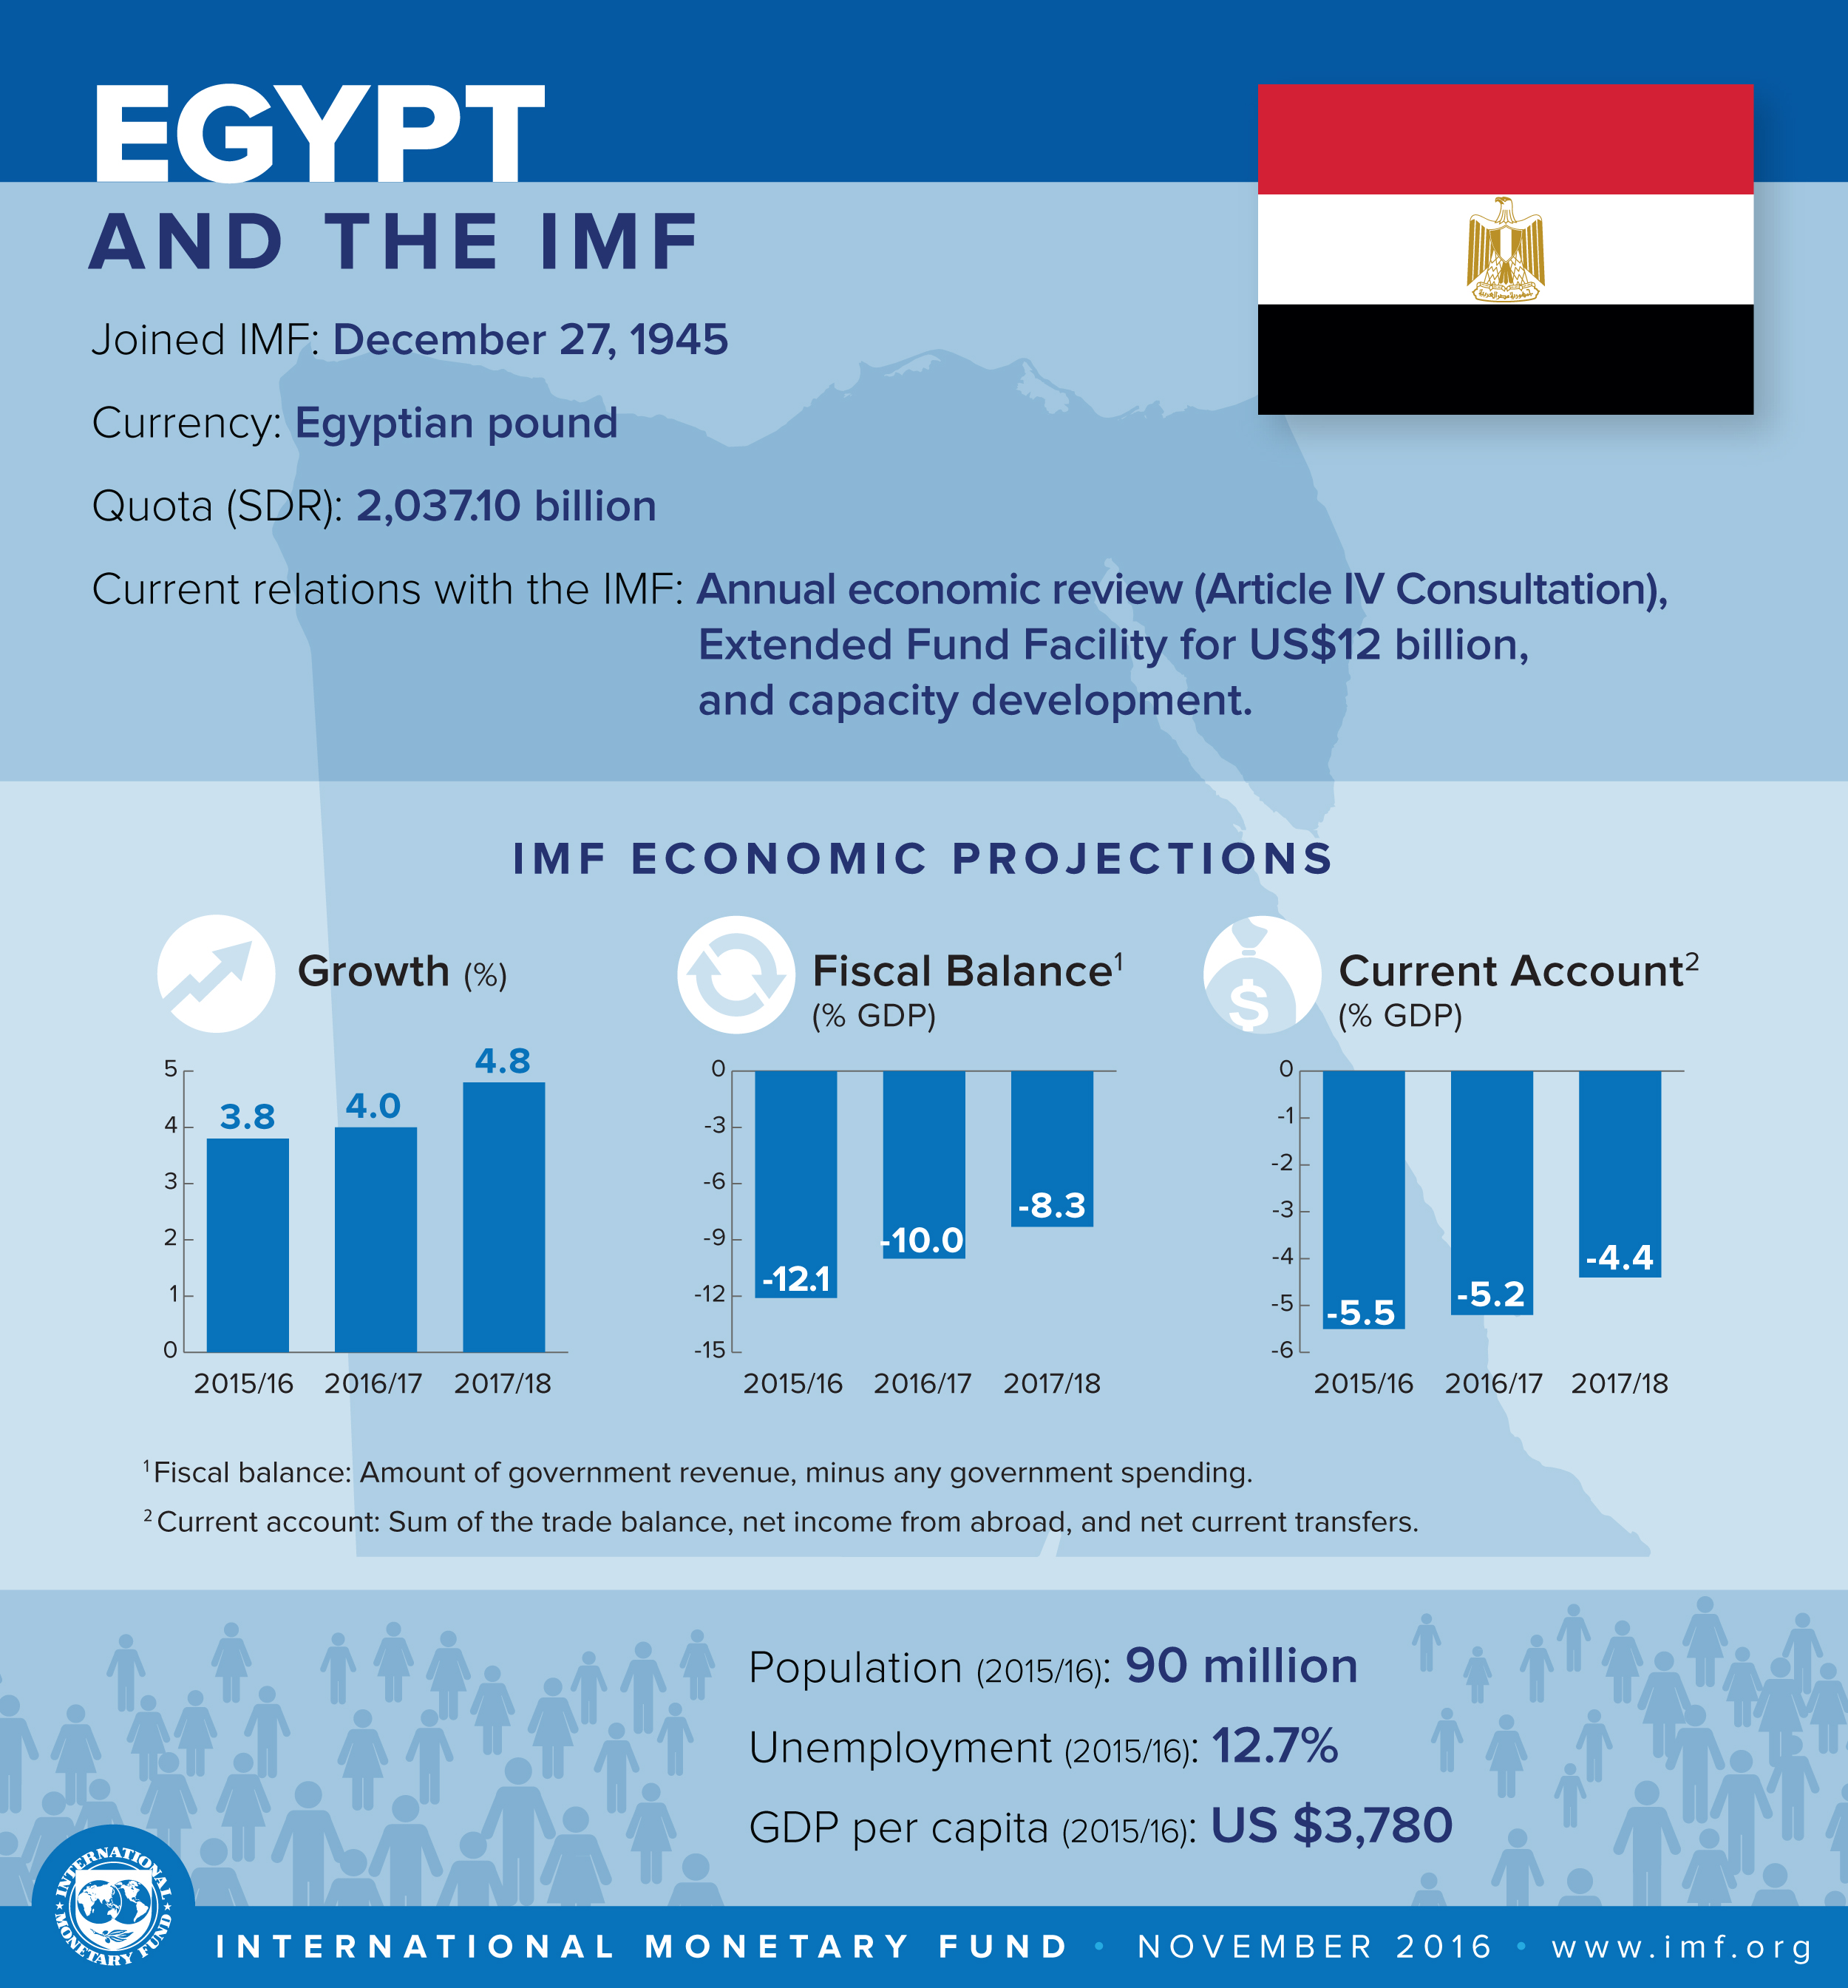
- On November 11, 2016, the Executive Board approved a three-year extended arrangement under the Extended Fund Facility (EFF) for the Arab Republic of Egypt for an amount equivalent to SDR 8.597 billion (about US$12 billion, or 422 percent of quota).
- The Executive Board’s approval allows for an immediate purchase of SDR 1.970 billion (or about US$2.75 billion).
- The remaining amount will be phased over the duration of the program, subject to five reviews.
Program Objectives and Expected Outcomes
- Restore macroeconomic stability and promote inclusive growth.
- Correct external imbalances and restore competitiveness.
- Place the budget deficit and public debt on a declining path.
- Boost growth and create jobs while protecting vulnerable groups.
- Programs aim to rebuild international reserves, reduce inflation to single digits, and encourage private sector-led growth.
Key Policy Measures (from Ms Christine Lagarde’s statement)
- Exchange rate and monetary policy:
- Liberalization of the exchange rate regime and devaluation of the Egyptian pound were highlighted as critical steps.
- The new exchange rate regime will be supported by prudently tight monetary policy.
- Fiscal consolidation:
- Introduction of a VAT, reduction of energy subsidies, and optimization of the public sector wage bill are key measures.
- Planned fiscal consolidation is projected to reduce public debt by almost 10 percentage points of GDP by the end of the program.
- Part of the fiscal savings will be used to strengthen social safety nets.
- Structural reforms:
- Focus on business licensing and insolvency frameworks; public financial management, including state-owned enterprises; energy sector and subsidy reforms; and labor market reform to increase labor market participation, especially among women and young people.
- Risk assessment:
- Risks to program implementation are significant but mitigated by the strength of the policy package, frontloading of major measures implemented as prior actions, and broad political support.
Recent Developments (Annex)
- Since 2011, political and regional developments led to macroeconomic imbalances: an overvalued exchange rate, depleted reserves, weak revenue, poorly targeted subsidies, and a growing public sector wage bill.
- 2014/15 measures: CBE devalued the Egyptian pound by 5 percent and increased interest rates; fuel and electricity prices were raised; subsidy bill fell by nearly 3 percent of GDP in FY 2014/15; a new Civil Service law was drafted; decision taken to replace the General Sales Tax with VAT.
- 2015/16 setbacks: momentum of reform slowed—planned fuel price increases deferred, income taxes were cut, capital gains tax postponed, parliamentary consideration of VAT delayed to 2016/17.
- 2015/16 outcomes: economy estimated to have grown by 3.8 percent; inflationary pressures increased; current account deficit widened; June 2016 reserves stood at about 3 months of prospective imports.
- Exchange rate pressures: devaluation of the official exchange rate by 13 percent in March 2016 did not restore market equilibrium; by end-September, the parallel market premium widened to more than 30 percent; official exchange rate estimated to be overvalued by about 25 percent in real effective terms.
Program Summary — Four Key Pillars
- Significant policy adjustment:
- (1) Liberalization of the foreign exchange system to eliminate forex exchange shortages and encourage investment and exports.
- (2) Monetary policy aimed at containing inflation.
- (3) Strong fiscal consolidation to ensure public debt sustainability.
- Strengthening social safety nets by increasing spending on food subsidies and cash transfers.
- Far-reaching structural reforms to promote higher and inclusive growth, increasing employment opportunities for youth and women.
- Fresh external financing to close financing gaps.
Main Elements of the Program
- Exchange rate, monetary and financial sector policies:
- On November 3 the CBE liberalized the foreign exchange system and adopted a flexible exchange rate regime.
- Monetary policy will focus on containing inflation and bringing it down to mid-single digits over the medium term.
- Measures include controlling credit to government and banks, strengthening the CBE’s capacity to forecast and manage liquidity, improving transparency and communication, and reviewing the supervisory model in line with Basel III principles.
- Fiscal policy, social protection and public financial management:
- Tax revenues are projected to increase by 2.5 percent of GDP over the program, largely due to implementation of VAT.
- Primary expenditures will be reduced by 3.5 percent owing to reduction of subsidies and containing the wage bill.
- About 1 percent of GDP out of achieved fiscal savings will be directed to additional food subsidies, cash transfers, and targeted social programs.
- Planned PFM reforms include regular review of operational performance of economic authorities; improved oversight of state issued guarantees; road map for pension reforms; and presentation of a budget statement on economic and public finance developments to parliament with every budget.
- Structural reforms and inclusive growth:
- Measures include streamlined industrial licensing, greater access to finance for SMEs, new insolvency and bankruptcy procedures, job intermediation schemes, specialized training programs for youth, increased availability of public nurseries, and improved safety of public transportation.
Selected Economic Indicators (2011/12–2016/17)
- Real GDP (market prices): 2.2; 2.1; 4.2; 3.8; 4.0 (2016/17 Prel./Proj. not labeled per year)
- Consumer prices (end of period): 7.3; 9.8; 8.2; 11.4; 14.0; 16.6
- Consumer prices (period average): 8.6; 6.9; 10.1; 11.0; 10.2; 18.2
- General Government Revenue and grants: 21.1; 21.9; 23.7; 20.3; 25.5
- Expenditures (incl. net acquisition of financial assets): 31.1; 35.3; 36.7; 33.5; 32.0; 33.1
- Of which: Interest: 5.6; 7.6; 8.1; 8.7
- Overall balance: -10.0; -13.4; -12.9; -11.5; -12.0
- Overall balance excl. grants: -10.6; -13.7; -16.5; -12.6; -12.2; -10.1
- Primary balance: -4.9; -6.3; -5.8; -4.8; -4.4; -1.8
- Gross Debt: 74.6; 84.8; 86.3; 89.0; 94.6; 93.8
- External: 9.3; 10.8; 9.9; 8.0; 7.7
- Domestic: 65.3; 74.0; 76.4; 81.0; 86.8; 83.7
- Budget sector (selected rows): 18.3; 19.0; 20.8; 19.1; 17.6; 22.9; 28.4; 33.9; 30.6; 29.4; 30.5
- Of which: Fuel subsidies: 5.8; 7.0; 6.6; 3.0; 2.6
- Of which: Food subsidies: 1.8; 1.7; 1.5; 1.4
- Monetary sector: Credit to the private sector: 7.1; 7.4; 16.7; 14.2; 8.3
- Reserve money6/: 5.1; 20.4; 14.8; 33.3; -1.6; 16.1
- Broad money (M2): 18.4; 17.1; 16.4; 18.6
- Treasury bill rate, 3 month (average, in percent): 13.4; 10.9; 11.8; 19.7
- External sector:
- Exports of goods (in U.S. dollars percentage change): -7.1; -3.2; -15.5; -15.2; 12.8
- Imports of goods (in U.S. dollars): 2.7; 2.4; 3.7; -7.4
- Merchandise trade balance: -11.3; -10.8; -11.2; -11.7; -11.0
- Current account: -2.2; -0.8; -5.5; -5.2
- Capital and financial account (incl. errors and omissions): 1.1; 0.9; 5.5; 4.6
- Foreign direct investment (net. In billions of US$): 3.6; 6.1; 6.7; 9.4
- External debt4/: 12.5; 15.1; 15.3; 14.3
- Gross international reserves (in billions of US$): 15.2; 14.5; 16.3; 19.5; 22.0
- In months of next year’s imports of goods and services: 2.5; 3.1
- In percent of short-term external debt5/: 308.8; 138.1; 191.9; 280.6; 267.8; 283.1
- Financing gap (in billions of US$): …
- Memorandum items:
- Nominal GDP (in billions of Egyptian pounds): 1,656.6; 1,843.8; 2,101.9; 2,429.8; 2,777.8; 3,434.1
- Nominal GDP (in billions of US$): 275.8; 285.4; 301.5; 330.2
- GDP per capita (in US$): 3,347; 3,370; 3,478; 3,710
- Unemployment rate (period average, percent): 12.4; 13.0; 12.9; 12.7; 12.3
- Poverty rate (percent): n.a.; 26.3
- Populations (in millions): 82.4; 84.7; 86.7; 90.2; 92.3
IMF Communications Department, Press Release No. 16/501 (November 11, 2016).